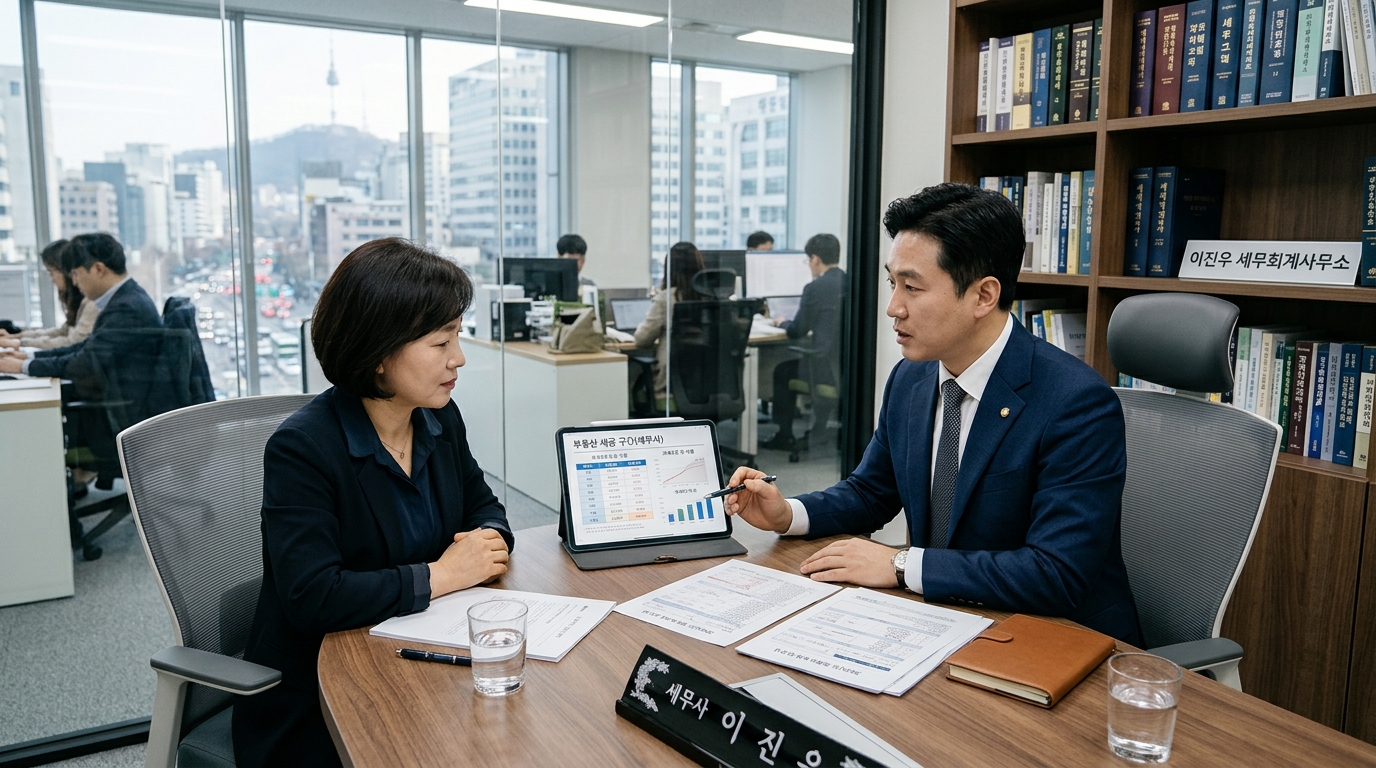
"내가 직접 살고 있는 집인가, 아니면 이름만 올려둔 집인가. 부동산 세금의 오랜 기준이었던 '주택 수'가 무너지고 '실거주 여부'와 '주택 가격'이 모든 세금을 결정하는 거대한 개편이 시작되었습니다. 시세 20억 이하 1주택자의 환호와 초고가 아파트 소유자의 보유세 급증이 엇갈리는 현장을 정밀 해부합니다."
신승엽 부동산·금융 전문기자|2026. 11. 09. 11:55 송고
▲ 공식 보도사진 — 서울 한강변 아파트 단지가 시원하게 내려다보이는 도심 사무실 책상 위에 2026 부동산 세제개편안 세부 시뮬레이션 보고서와 계산기가 놓여 있다. 실거주 1주택자 기본공제 14억 상향과 초고가 주택 중과 조치가 맞물리며 부동산 시장의 셈법이 복잡해졌다.
정부가 실거주 중심 과세 체계 개편을 골자로 한 2026 부동산 세제개편안을 내놓으면서 실거주 1주택 종부세 14억 상향과 초고가·다주택 보유세 중과를 둘러싼 시장의 셈법이 복잡하게 얽혀들고 있습니다.
그동안 주택 시장을 지배해 왔던 "집이 몇 채인가"라는 징벌적 다주택 과세의 틀이 깨지고, "실제로 들어가 살고 있는가"와 "그 집이 얼마짜리인가"가 세금의 크기를 좌우하는 새로운 시대가 열렸습니다. 실제로 내 집에서 생활하는 중산층 1주택자에게는 파격적인 세금 감면 혜택이 주어지지만, 수십억 원을 호가하는 초고가 주택이나 전세를 끼고 사둔 비거주 1주택자에게는 매서운 세금 청구서가 예고된 것입니다.
이에 따라 서울 강남의 초고가 단지는 매수 문의가 뚝 끊기며 관망세에 들어간 반면, 마포와 용산, 성동구 등 한강변 중상급지 아파트로는 절세 수요가 대거 몰리는 이른바 '풍선효과'까지 나타나고 있습니다. 이번 세제개편안이 내 집 마련과 보유세에 어떤 변화를 가져오는지, 세부 조항과 시뮬레이션을 통해 알기 쉽게 짚어보겠습니다.
1. 실거주 1주택 14억 완화 vs 초고가 핀셋 중과… 2026 세제개편의 핵심 골자
이번 2026 부동산 세제개편안의 가장 큰 특징은 철저한 '실거주자 우대'와 '초고가 주택 핀셋 과세'로 요약할 수 있습니다. 가장 눈에 띄는 변화는 1세대 1주택 실거주자의 종합부동산세 기본공제 금액이 현행 공시가격 12억 원에서 14억 원으로 2억 원 상향 조정된다는 점입니다.
공시가격 14억 원은 현재 시세로 환산하면 약 20억 원 안팎의 아파트에 해당합니다. 즉, 마포나 영등포, 강동 등 서울 주요 지역의 전용 84㎡ 아파트에 실제로 거주하는 1주택자라면 이제 종부세를 단 1원도 내지 않아도 되는 비과세 혜택을 누리게 됩니다. 다만 살지 않고 세를 준 비거주 1주택자는 당초 정부가 9억 원까지 깎으려다 반발에 부딪혀 현행 12억 원을 유지하기로 절충점을 찾았습니다.
반면 시세 32억 원(과세표준 6억 원)을 초과하는 초고가 아파트에 대해서는 과세의 칼날이 한층 날카로워졌습니다. 과표 6억~12억 원 구간의 세율이 1.0%에서 1.3%로 껑충 뛰고, 세금을 매기는 기준이 되는 공정시장가액비율 역시 1주택자는 60%에서 70%로, 다주택자는 80%까지 상향됩니다. 고가 아파트를 가진 사람일수록 과세표준이 눈덩이처럼 불어나 세 부담이 급증하는 구조입니다.
▲ 현장 취재사진 — 서울 시내 한 전문 세무사 사무실에서 세무사가 의뢰인에게 2026 세제개편에 따른 양도세 장기거주공제 적용 스케줄을 설명하고 있다. 단순히 집을 오래 보유하기만 해서는 감면을 받을 수 없게 되면서 실거주 요건을 채우려는 문의가 쇄도하고 있다.
2. 세액공제 금액 한도 신설의 충격… 시가 35억 이상 종부세 급증 시뮬레이션
초고가 주택 소유자들에게 가장 뼈아픈 대목은 바로 '고령자·장기보유 세액공제 금액 한도'의 신설입니다. 그동안 은퇴한 고령층은 집값이 아무리 비싸도 나이가 60세를 넘고 10년 이상 오래 거주하면 종부세를 최대 80%까지 깎아주었습니다.
하지만 개편안은 공제율 80%라는 비율 자체는 남겨두되, 실제로 깎아주는 '금액의 상한선'을 법으로 못 박아버렸습니다. 2027년에는 최대 800만 원, 2028년부터는 최대 600만 원까지만 세금을 깎아줍니다. 계산상 공제액이 2,000만 원이 나오더라도 실제로는 600만 원만 감면받고 나머지는 고스란히 현금으로 내야 한다는 뜻입니다.
정부 시뮬레이션 결과에 따르면, 시가 약 35억 원을 분기점으로 세금의 방향이 정반대로 갈립니다. 시가 20억 원 아파트는 종부세가 27만 원에서 10만 원대로 줄어들고, 30억 원 아파트도 91만 원에서 76만 원으로 소폭 감소합니다. 그러나 시가 40억 원 아파트는 262만 원에서 325만 원으로 뛰고, 시가 50억 원 아파트는 453만 원에서 무려 978만 원으로 두 배 이상 폭증합니다. 70억 원대 초고가 펜트하우스는 세금이 937만 원에서 3,295만 원으로 무려 3.5배나 치솟게 됩니다.
과세 구분 항목
현행 제도 (2026년 기준)
2026 개편안 (2027년 이후)
제도 개편에 따른 시장 영향
실거주 1주택 기본공제
공시가격 12억 원
공시가격 14억 원 (상향)
시세 약 20억 원 이하 1주택 종부세 전액 면제
비거주 1주택 기본공제
공시가격 12억 원
공시가격 12억 원 (유지 절충)
실거주 여부에 따른 보유세 격차 발생
다주택자 기본공제
공시가격 9억 원
공시가격 9억 원 (현행 유지)
2주택 이상 합산 과세로 다주택 보유 압박 지속
공정시장가액비율
1주택 60% / 다주택 60%
1주택 70% / 다주택 80%
과세표준 상향으로 고가·다주택 세 부담 급증
세액공제 금액 한도
금액 한도 없음 (최대 80% 전액)
2027년 800만 원 / 2028년 600만 원
시가 35억 초과 고가 1주택자 실효 감면액 축소
3. 보유만 해선 감면 없다… 양도소득세 '장기거주소득공제' 전환의 파장
보유세인 종부세뿐만 아니라 집을 팔 때 내는 양도소득세에서도 엄청난 지각변동이 일어납니다. 지금까지 10년 이상 집을 가지고 있으면 세금을 최대 80%까지 깎아주던 '장기보유특별공제(장특공제)'가 '장기거주소득공제'라는 이름으로 완전히 탈바꿈합니다.
단순히 등기부등본에 이름을 올려두고 오래 가지고 있었다는 이유만으로는 세금을 깎아주지 않겠다는 취지입니다. 2027년까지는 보유기간과 거주기간을 반반씩 인정해 주지만, 2028년부터 보유공제 비율이 연 2%로 줄어들고, 마침내 2029년부터는 보유기간에 대한 공제가 '0%'로 완전히 사라집니다. 오직 그 집에 '실제로 거주한 기간'만 매년 8%씩 계산해 줍니다.
만약 어떤 사람이 12억 원에 산 아파트를 10년 동안 가지고 있다가 32억 원에 팔았다고 가정해 보겠습니다. 10년 동안 딱 2년만 살고 8년은 전세를 주었다면, 2027년에 팔 때는 양도세가 2억 3,600만 원이지만, 2029년에 팔면 양도세가 4억 500만 원으로 무려 1억 6,900만 원(71.6%)이나 폭증합니다. 집주인들이 서둘러 실거주를 채우러 들어가거나 아예 집을 팔지 못하는 혼란이 예고되는 대목입니다.
▲ 생활 밀착 취재사진 — 서울 시내 한 아파트 거실에서 은퇴한 고령 부부가 재산세와 종부세 고지서를 앞에 두고 깊은 고민에 잠겨 있다. 고정 수입이 없는 고령층의 경우 공정시장가액비율 상향과 세액공제 한도 신설로 건강보험료 피부양자 자격까지 박탈될 위기에 놓였다.
4. '강남 대신 마·용·성' 절세형 똘똘한 한 채 쏠림과 수도권 양극화
세제개편안의 신호는 부동산 시장의 판도를 빠르게 흔들고 있습니다. 세금 폭탄을 맞게 된 시가 35억 원 이상의 강남권 초고가 아파트는 매수세가 뚝 끊겼습니다. 반면 기본공제 14억 상향으로 종부세 부담이 거의 사라진 시세 20억~30억 원대 준상급지로는 매수세가 몰리는 기현상이 나타나고 있습니다.
이른바 '강남 대신 마·용·성(마포·용산·성동)'으로 대표되는 '절세형 똘똘한 한 채' 갈아타기 바람입니다. 실제로 마포래미안푸르지오나 옥수·금호동 일대의 20억 원대 아파트는 매수 문의가 잇따르며 호가가 오르고 있습니다. 서초구 반포자이 84㎡의 보유세가 1,810만 원에서 2,257만 원으로 27% 뛰고 한남더힐 대형 평형이 1억 원을 훌쩍 넘는 세금을 내야 하는 것과 달리, 마포나 영등포 단지는 세금이 오히려 줄어들거나 면제되기 때문입니다.
이로 인해 서울 내부에서는 강남 고가 주택의 가격 상승세가 꺾이며 상위 20%와 하위 20%의 격차를 나타내는 5분위 배율이 6.4에서 6.2로 낮아졌습니다. 하지만 수도권 전체로 눈을 돌리면 판교나 분당 등 경기 남부 핵심지만 오르고 외곽은 침체하면서 5분위 배율이 역대 최고치인 9.7까지 치솟아 수도권 양극화가 극에 달하고 있습니다.
단지명 및 전용면적
지역 및 입지 특성
현행 총 보유세 (재산세+종부세)
개편 후 총 보유세 (추정)
세부담 변동률
용산구 한남더힐 (235㎡)
용산 초고가 대표 단지
약 7,633만 원
1억 850만 원 (내후년 1.48억)
44.7% 급증
서초구 반포자이 (84㎡)
강남권 초고가 랜드마크
약 1,810만 원
약 2,257만 원
27.0% 증가
강남구 래미안대치팰리스 (84㎡)
대치동 학군 최고 선호지
약 1,500만 원
약 1,855만 원
25.0% 증가
마포구 마포래미안푸르지오 (84㎡)
마포 한강변 준상급지
약 416만 원
약 411만 원
소폭 감소 (절세)
영등포구 당산동 래미안4차 (84㎡)
서남권 핵심 역세권 단지
종부세 과세 대상 포함
종부세 전액 면제 (비과세)
11~12% 감소
5. 고령 은퇴자의 건보료 폭탄 위기와 매물 잠김·임대료 전가 우려
이번 개편안에는 정책의 사각지대에서 신음하는 목소리도 적지 않습니다. 가장 심각한 계층은 강남 3구에 평생 살아온 고령 은퇴자들입니다. 통계에 따르면 강남 3구 집합건물 소유자의 무려 47.9%(38만 6,000명)가 60세 이상 고령층입니다.
매달 들어오는 월급이 없는 고령 은퇴자들은 공정시장가액비율이 70%로 오르면서 보유세가 수백만 원씩 늘어납니다. 더 무서운 것은 과세표준이 뛰면서 자녀의 건강보험에 얹혀 있던 '피부양자 자격'이 강제로 박탈되어 매달 수십만 원의 지역건보료를 따로 내야 한다는 점입니다. 여기에 기초연금 수급 자격까지 떨어져 생계 압박이 가중되고 있습니다.
국회 예산정책처는 이번 개편으로 향후 5년 동안 무려 12조 6,000억 원의 세수가 더 걷힐 것으로 내다봤습니다. 하지만 세금을 무겁게 매겨 집을 팔게 만들겠다는 정부의 의도와 달리, 양도세까지 함께 강화되면서 집주인들이 집을 파는 대신 증여를 택하거나 버티기에 들어가는 '매물 잠김(동결효과)'이 나타나고 있습니다. 결국 늘어난 세금 부담이 고스란히 전월세 가격 인상으로 이어져 무주택 세입자에게 전가될 수 있다는 우려가 커지고 있습니다.
양도 시점 (매도 연도)
실거주 기간 공제율
단순 보유기간 공제율
합산 최대 공제율
공제 한도액 (세액공제 상한)
2027년까지 (현행 유지)
연 4%씩 적립 (최대 40%)
연 4%씩 적립 (최대 40%)
최대 80% 공제
금액 한도 없음
2028년 양도분
연 6%씩 적립 (최대 60%)
연 2%씩 적립 (최대 20%)
최대 80% 공제
최대 20억 원 한도 제한
2029년 이후 양도분
연 8%씩 적립 (최대 80%)
공제 없음 (0% 전면 폐지)
최대 80% 공제
최대 10억 원 한도 제한
6. 세금 고지서 받기 전 필수 체크… 비거주 예외 인정과 절세 체크리스트
새로운 세법 체계 속에서 내 소중한 자산을 지키려면 미리미리 꼼꼼한 세무 점검을 거쳐야 합니다. 특히 부득이한 사정으로 내 집에 들어가 살지 못하는 경우 정부가 마련한 '예외 규정'을 반드시 챙겨야 합니다.
1년 이상 계속 거주한 적이 있다면 직장 전근이나 이직, 자녀 대학 진학, 1년 이상의 질병 치료나 요양, 60세 이상 부모 봉양 등의 사유가 있을 때 최장 3년까지는 실제로 산 것으로 인정받을 수 있습니다. 또한 재건축이나 재개발로 집이 헐려 나와 사는 기간도 공사 기간의 50%를 거주 기간으로 인정해 줍니다.
집을 팔아야 할지, 증여해야 할지 고민이라면 과세기준일인 6월 1일 전에 주민등록초본의 주소 변동 내역을 떼어 실제 누적 거주 기간을 정확히 계산해야 합니다. 만 65세 이상이고 10년 이상 거주한 1주택자라면 상속이나 증여 시점까지 종부세 납부를 미룰 수 있는 '납부유예 제도'를 활용하는 것도 고령 은퇴자에게 훌륭한 탈출구가 될 수 있습니다.
2026 부동산 세제개편 핵심 FAQ
Q1. 부부 공동명의인 경우 종부세 기본공제는 어떻게 계산되나요?
부부 공동명의는 각자 1인당 9억 원씩 총 18억 원의 기본공제를 받거나, 1세대 1주택 단독명의 특례를 신청해 14억 원 공제와 고령자·장기보유 세액공제를 선택해 적용받을 수 있습니다. 보유 기간과 연령에 따라 유불리를 비교해 유리한 쪽을 신청해야 합니다.
Q2. 비거주 1주택자는 실거주 1주택자와 세금 차이가 얼마나 나나요?
공시가격 15억 원(시세 22억 원) 아파트 기준으로 10년 실거주자의 종부세는 약 10만 8,000원에 불과하지만, 거주하지 않고 세를 준 비거주 1주택자는 약 152만 1,000원을 내야 해 무려 14배의 세금 격차가 발생합니다.
Q3. 양도세 장기거주공제를 채우기 위해 위장전입을 하면 어떻게 되나요?
국세청은 신용카드 사용 내역, 휴대전화 기지국 위치, 관리비 전기·수도 사용량, 자녀 학교 통학 기록 등을 전산으로 정밀 교차 검증합니다. 위장전입이 적발되면 감면 세액 추징은 물론 최고 40%의 부당과소신고가산세가 부과되므로 절대 피해야 합니다.
In-Depth AnalysisEconomy & Real Estate
[In-Depth Analysis] Dual Impact of 2026 Real Estate Tax Reforms: KRW 1.4B Comprehensive Tax Relief vs Surcharges on Ultra-Luxury Properties
"Does the homeowner actually reside in the property, or merely hold title? South Korea is executing a fundamental tax restructuring that replaces property counts with actual owner-occupancy and property valuation as decisive metrics. While middle-class homeowners celebrate comprehensive tax relief up to KRW 1.4 billion, ultra-luxury owners face soaring tax obligations."
Seung Youb Ssin, Senior Real Estate & Financial Correspondent|Published Nov 09, 2026, 11:55 KST
▲ Official Press Photo — Detailed simulation reports and tax calculators laid out on a high-rise office desk overlooking the Han River apartment skyline in Seoul. The 2026 tax overhaul introduces a KRW 1.4 billion deduction for owner-occupiers while levying targeted surcharges on luxury properties. (Press Archive)
South Korea unveiled its 2026 real estate tax overhaul centered on owner-occupancy principles, sparking widespread financial calculations as single-homeowner comprehensive tax exemptions rise to KRW 1.4 billion while ultra-luxury and multi-home assets face targeted surcharges.
For years, real estate taxation penalized individuals simply for holding multiple titles. Under the newly designed framework, owner-occupancy status and total asset valuation have replaced property count as decisive criteria. Genuine owner-occupiers residing in middle-income homes enjoy substantial tax exemptions, whereas luxury properties and absentee owners face steep tax hikes.
Consequently, buying sentiment across prime Gangnam complexes has cooled as owners adopt a wait-and-see stance. In contrast, residential districts such as Mapo, Yongsan, and Seongdong have experienced an influx of buyers seeking tax-efficient single homes. This report analyzes the statutory mechanisms, property simulations, and market impacts.
1. KRW 1.4B Deduction for Owner-Occupiers vs Surcharges on Luxury Properties
The defining pillar of the 2026 reform is the preferential treatment of bona fide owner-occupiers paired with targeted surcharges on luxury real estate. Most notably, the statutory base deduction for single-homeowner Comprehensive Real Estate Holding Tax increases from KRW 1.2 billion to KRW 1.4 billion based on officially assessed valuations.
An assessed value of KRW 1.4 billion correlates roughly to a market price around KRW 2.0 billion. Consequently, owner-occupiers residing in standard 84-square-meter apartments across Seoul middle-tier boroughs are entirely exempt from holding taxes. Meanwhile, absentee single-home owners remain capped at the existing KRW 1.2 billion threshold after authorities compromised following public backlash.
Conversely, properties with tax bases exceeding KRW 600 million (market valuations above KRW 3.2 billion) face elevated tax brackets. Tax rates for brackets between KRW 600 million and KRW 1.2 billion rise from 1.0 percent to 1.3 percent. Additionally, statutory fair market value ratios expand from 60 percent to 70 percent for single homeowners and to 80 percent for multi-homeowners, significantly widening taxable bases.
▲ Editorial Documentary Photo — A certified tax accountant in Seoul explains the transitional schedule of the long-term residency deduction to a client. Because holding tenure without physical residency no longer guarantees capital gains deductions, inquiries regarding physical relocation are escalating rapidly. (Press Archive)
For owners of ultra-luxury properties, the most consequential intervention is the introduction of statutory monetary ceilings on senior and long-term holding deductions. Previously, qualifying seniors over age 60 residing in homes for a decade received cumulative deductions up to 80 percent without financial caps.
While the nominal 80 percent ratio remains intact, the reform establishes strict statutory monetary limits. Maximum allowable deductions are capped at KRW 8.0 million in 2027 and further compressed to KRW 6.0 million from 2028 onward. Even if mathematical calculations yield KRW 20 million in tax credits, realized relief cannot exceed KRW 6.0 million.
Government simulations confirm that holding tax liabilities diverge sharply around the KRW 3.5 billion market threshold. Homes valued at KRW 2.0 billion see annual taxes decline from KRW 276,000 to approximately KRW 108,000. KRW 3.0 billion properties see modest reductions from KRW 910,000 to KRW 760,000. However, KRW 4.0 billion assets experience increases from KRW 2.62 million to KRW 3.25 million, while KRW 5.0 billion residences see obligations more than double from KRW 4.53 million to KRW 9.78 million.
Tax Assessment Category
Current Framework (2026 Baseline)
2026 Overhaul (2027 Onward)
Market Ramifications & Strategic Shifts
Owner-Occupier Base Deduction
Assessed KRW 1.2 Billion
Assessed KRW 1.4 Billion (Raised)
Complete tax exemption for homes valued under KRW 2.0B
Absentee Single-Home Deduction
Assessed KRW 1.2 Billion
Assessed KRW 1.2 Billion (Preserved)
Widening tax divergence based on residency verification
Multi-Homeowner Base Deduction
Assessed KRW 900 Million
Assessed KRW 900 Million (Unchanged)
Sustained holding pressure across multiple property titles
Fair Market Value Ratio
60% Single / 60% Multi
70% Single / 80% Multi
Expands taxable base, driving substantial tax hikes on luxury assets
Tax Deduction Monetary Ceiling
No monetary cap (Full 80% applied)
KRW 8.0M in 2027 / KRW 6.0M in 2028
Reduces effective relief for homes valued above KRW 3.5B
3. Transition to Long-Term Residency Capital Gains Deductions
Beyond recurring holding taxes, transaction taxation experiences a profound realignment as the conventional Special Deduction for Long-Term Holding transforms into a Long-Term Residency Income Deduction.
Under the revised doctrine, passive title ownership without residency yields zero tax relief. Through 2027, holding and residency periods contribute equally at 4 percent per year. Beginning in 2028, holding contributions drop to 2 percent annually while residency jumps to 6 percent. From 2029 onward, holding allowances are eliminated entirely, awarding deductions exclusively at 8 percent per year of documented physical residency up to an 80 percent maximum.
Consider an asset acquired for KRW 1.2 billion and sold for KRW 3.2 billion after a decade of ownership. If the owner resided in the unit for only two years while leasing it out for eight, capital gains tax owed in 2027 equals KRW 236 million. By 2029, due to the termination of holding deductions, the tax jumps to KRW 405 million—a surge of KRW 169 million (71.6%).
▲ Domestic Documentary Photo — An elderly retired couple reviews property holding tax documentation in their living room. Lacking recurring wages, senior citizens face severe cash flow pinches as higher assessment ratios threaten health insurance dependency status. (Press Archive)
4. Capital Inflow into Middle-Tier Districts and Capital Region Divergence
Tax restructuring has reshaped metropolitan capital allocation. Confronted with surcharges, buyer interest in Gangnam luxury units has plateaued. Conversely, buyers seeking tax-efficient single assets are directing capital into middle-tier riverfront locations such as Mapo, Yongsan, and Seongdong.
Properties in the KRW 2.0 billion to KRW 3.0 billion range across Mapo and Seongdong are experiencing upward pricing momentum. While Banpo Xi 84-square-meter units face a 27 percent tax increase from KRW 18.1 million to KRW 22.57 million, complexes such as Mapo Raemian Prugio enjoy slight holding tax reductions, stimulating selective demand.
This dynamic has compressed Seoul internal wealth quintile ratio from 6.4 down to 6.2, as luxury gains stall while mid-tier values rise. However, across the broader metropolitan area, southern employment hubs continue expanding while outer provincial zones stagnate, driving the regional quintile ratio to an unprecedented 9.7.
Complex Name & Floor Area
District & Strategic Location
Current Total Holding Tax
Projected Total Holding Tax
Anticipated Percentage Change
Yongsan Hannam the Hill (235 sqm)
Prime Luxury Enclave
Approx. KRW 76.33 Million
KRW 108.50 Million
44.7% Surge
Seocho Banpo Xi (84 sqm)
Core Gangnam Benchmark
Approx. KRW 18.10 Million
KRW 22.57 Million
27.0% Increase
Gangnam Raemian Daechi Palace (84 sqm)
Premier School District
Approx. KRW 15.00 Million
KRW 18.55 Million
25.0% Increase
Mapo Raemian Prugio (84 sqm)
Mid-Tier Waterfront Hub
Approx. KRW 4.16 Million
KRW 4.11 Million
Slight Reduction (Tax Relief)
Yeongdeungpo Dangsan Raemian 4th (84 sqm)
Subway Transit Junction
Taxable Under Prior Rules
Complete Holding Tax Exemption
11% to 12% Reduction
5. Liquidity Pressures on Senior Retirees and Supply Freeze Concerns
Policy analysts emphasize unintended repercussions affecting fixed-income seniors. In the three core Gangnam districts, 47.9 percent of multifamily property owners (386,000 individuals) are aged 60 or older.
Lacking monthly wages, retired seniors face sharp holding tax increases as fair market value ratios climb to 70 percent. Higher taxable bases also jeopardize dependent coverage under National Health Insurance, triggering steep standalone regional premiums and disqualifying households from basic pensions.
The National Assembly Budget Office projects an additional KRW 12.6 trillion in tax revenues over five years. However, with both holding and transaction taxes elevated, homeowners frequently choose long-term retention or gift transfers rather than open-market sales, inducing severe lock-in effects. Economists caution that increased tax overheads will ultimately be passed onto unhoused tenants through elevated monthly rents.
Disposition Timeline (Sale Year)
Residency Tenure Deduction Rate
Passive Holding Deduction Rate
Cumulative Maximum Deduction
Statutory Monetary Deduction Cap
Through 2027 (Current Policy)
4% per year (Max 40%)
4% per year (Max 40%)
Maximum 80% Deduction
No Monetary Limit Applied
2028 Dispositions
6% per year (Max 60%)
2% per year (Max 20%)
Maximum 80% Deduction
Capped at KRW 2.0 Billion
2029 Dispositions Onward
8% per year (Max 80%)
Zero (Completely Eliminated)
Maximum 80% Deduction
Capped at KRW 1.0 Billion
6. Mandatory Compliance Checkpoints and Statutory Residency Exemptions
To defend asset value, owners must audit their tax exposure ahead of assessment dates. Authorities have established statutory exceptions granting up to three years of recognized residency for valid life disruptions.
Following one year of continuous residency, exemptions apply for employment transfers, higher education enrollment, certified medical treatments lasting over one year, overseas assignments, and caring for elderly dependents aged 60 or older. Additionally, 50 percent of reconstruction downtime is credited toward residency requirements without falling under the three-year ceiling.
Prior to the June 1 taxation benchmark, taxpayers should examine certified residency histories to verify cumulative owner-occupancy periods. Senior homeowners aged 65 and older who have resided in properties for over a decade should explore tax deferral provisions, which allow holding tax settlements to be postponed until eventual inheritance or gift transfers.
Real Estate Tax Overhaul FAQ
Q1. How are holding tax deductions calculated for jointly owned married couples?
Couples holding joint ownership can either claim KRW 900 million deductions per individual (totaling KRW 1.8 billion) or elect single-homeowner special treatment offering a KRW 1.4 billion deduction alongside senior age and tenure credits, choosing whichever yields minimal tax.
Q2. What is the tax disparity between owner-occupiers and absentee owners?
For an apartment assessed at KRW 1.5 billion (market price KRW 2.2B), a 10-year owner-occupier pays approximately KRW 108,000, whereas an absentee owner pays KRW 1.52 million—a 14-fold disparity.
Q3. What penalties occur if false residency registrations are discovered?
The National Tax Service cross-examines utility consumption, credit card histories, and mobile location logs. Fraudulent residency results in full clawbacks of deducted sums alongside statutory underreporting surcharges up to 40 percent.
PRO SOURCING ENGINE만인의 탑 빅데이터 솔루션
★ 가입 시 600 크레딧(120회) 전원 무료
내가 찾는 상품 키워드, 지금 얼마나 검색될까?
네이버 월간 검색량 + 구글 볼륨 + 아이템스카우트 실시간 상품수와 경쟁강도 배지를 0.5초 만에 무료로 확인하세요.
MANINTOP NEWSLETTER
📬 만인의 탑 뉴스레터 무료 구독
오늘 보신 정책·시사 뉴스가 유익하셨나요? 매일 엄선되는 알짜 복지 혜택과 국회 실시간 속보를 이메일로 가장 먼저 받아보세요. (평생 무료)
1월이 시작되면 감기는 이미 우리 곁에 와 있습니다. 2월, 3월, 4월까지 이어지는 추위와 건조함은 코와 목을 가장 먼저 공격합니다. 아침에 일어나자마자 막혀 있는 코. 계속 흐르는 콧물. 괜히 칼칼해지는 목. 이 증상은 “시작”일 뿐입니다. 한 번 무너지면 일주일, 길면 한 달까지 끌고 갑니다. 약을 먹으면 잠깐 괜찮아집니다. 하지만 며칠 뒤 또 반복됩니다. 왜일까요? 감기는 ‘치료’의 문제가 아니라 ‘관리’의 문제이기 때문입니다. 대부분은 감기가 오고 나서 약을 찾습니다. 하지만 진짜 중요한 건 감기가 오기 전에 코와 목을 지키는 것입니다. 건조한 실내 공기, 차가운 바깥 공기, 눈에 보이지 않는 세균. 코와 목은 매일 공격받고 있습니다. 지긋지긋하죠! 그런데도 우리는 아무 준비 없이 버티고 있습니다. 이번 겨울도 그렇게 보낼 건가요? 사실 방법은 어렵지 않습니다. 코를 깨끗하게 관리하고, 목을 따뜻하게 보호하고, 점막을 촉촉하게 유지하고, 기관지를 미리 관리하고, 외부 공기를 차단하는 것. 이 다섯 가지만 꾸준히 해도 감기약 없이 겨울을 보내는 것이 충분히 가능합니다. 🔥 이제부터 그 방법을 하나씩 살펴보겠습니다. 🔥 1. 코와 목을 먼저 관리해야 하는 과학적 이유 감기의 대부분은 코 점막에서 시작됩니다. 국제 학술지 Nature Reviews Microbiology 와 Journal of Allergy and Clinical Immunology 에 실린 호흡기 감염 관련 연구들에서는, 감기 바이러스가 비강 상피세포에 먼저 부착해 증식한다는 점을 설명하고 ...
리모델링사업이 진행 중인 아파트를 매매할 때 “계약금 10%를 언제까지 내야 하느냐”는 질문이 특히 많이 나옵니다. 이주공고(이주 안내)가 7~11월쯤이라고 들으면, 그 시점에 맞춰 계약금도 움직일 것 같아서 더 헷갈리기 쉽습니다. 하지만 실제 납부기한은 ‘이주공고가 언제냐’만으로 자동 결정되지 않는 경우가 많습니다. 1) 계약금 10% 납부기한: 결국 ‘문서에 적힌 일정’이 기준 계약금 10%를 언제까지 납부해야 하는지는, 내가 서명하는 매매계약서(특약 포함) 와 사업주체/조합이 제시한 공고·안내문 에 적힌 납부 일정이 기준이 됩니다. 실제 공고문에서는 분양대금 납부의 큰 틀(계약금→중도금→잔금)을 먼저 안내하고, 상세 일정은 별도 표나 유의사항으로 제시하는 방식이 흔합니다. 또, 계약서 문구에 따라 지급 시점이 조건부로 설정될 수도 있습니다. 예를 들어 한 사례 소개 자료에서는 용역계약서에 잔금(10%) 지급시기가 “사업승인 후”로 기재되어 있었다는 점이 언급됩니다. 이런 식으로 ‘사업 단계’와 지급을 연동하는 문구가 들어가면, 질문의 답은 계약서 문구를 확인해야만 확정됩니다. 관련 내용은 링크 에서 문구 사례를 확인할 수 있습니다. 2) 입주자모집공고에서 확인되는 ‘납부 순서’와 잔금 마감 시점 공고문에 적힌 문구를 보면, 납부 순서와 잔금 마감에 대한 기준이 비교적 명확하게 제시되는 경우가 있습니다. 예를 들어 한 입주자모집공고에는 “분양금액(주택가격)은 계약금, 중도금, 잔금의 순서로 납부”하며 “잔금은 입주(열쇠 수령일) 전에 완납”해야 한다고 안내되어 있습니다. (문구 확인: 링크 ) 이 문구가 의미하는 바는 최소 2가지입니다. 분양/공급 형태의 문서에서는 ‘계약금→중도금→잔금’ 흐름이 공식적으로 안내될 수 있습니다. 잔금은 “입주(열쇠 수령)” 이전에 완납해야 한다는 마감 기준이 문서에 적혀 있을 수 있습니다. 다만, 위 공고문 문구는 잔금 마감에 대한 기준을 보여주지만, 계약금 10%의...
윤석열 전 대통령 탄핵 인용 소식을 접하면, 가장 궁금한 지점은 ‘헌재가 정확히 무엇을 위헌·위법으로 봤는가’입니다. 또한 탄핵과 별개로 진행되는 형사재판(내란 우두머리 혐의 등)이 어디까지 왔는지도 함께 정리할 필요가 있습니다. 아래 내용은 제공된 기사/게시물 스니펫과 링크에서 확인되는 범위만 모아, 일반인이 흐름을 이해하기 쉽게 정리한 것입니다. 1) 탄핵 인용 관련: 스니펫에서 확인되는 ‘판단의 골격’ 제공된 근거 중 조국혁신당 사이트에는 헌법재판소가 윤석열 탄핵 심판에서 “피청구인의 위헌·위법행위는 국민 신임 …”이라는 취지로 판단했다는 문장이 인용돼 있습니다( 링크 ). 이 인용문만 놓고 보면, ‘위헌·위법행위’가 있었는지와 그로 인해 ‘국민의 신임’이 어떻게 평가됐는지가 핵심 축으로 소개됩니다. 다만 질문에서 요청하신 세부 항목, 즉 비상계엄 선포 자체를 문제 삼은 구체적 이유, 계엄 이후 조치(포고령, 국회 통제 등)의 어떤 지점이 헌법 위반인지, 국회의 권한행사 방해 및 정치활동 제약을 어떤 논리로 판단했는지 등은, 이번에 제공된 근거의 제목/스니펫만으로는 조항·사실관계·판단 구조가 그대로 제시돼 있지 않습니다. 따라서 이 글에서는 ‘헌재가 무엇을 문제 삼았다’는 세부 리스트를 단정적으로 재구성하기보다, 현재 확인 가능한 문구 수준의 요약(위헌·위법행위 → 국민 신임의 문제로 평가)까지만 적습니다. 만약 헌재 결정문 전문(주문 및 이유)이 추가로 확인되면, 그때는 문장 단위로 ‘어떤 행위’와 ‘어떤 헌법 원리/조항’이 연결되는지(예: 권력분립, 국회의 권한, 정치적 기본권 등) 구조화해 정리하는 것이 가장 정확합니다. 2) 형사 절차(내란 혐의) 관련: 체포영장과 1심 선고 언급 탄핵 심판과 별도로, 12·3 비상계엄 사태로 내란 혐의를 받는 윤석열 대통령에 대해 2024년 12월 31일 체포 영장이 발부됐다는 BBC 보도가 있습니다( 링크 ). 해당 보도는 ‘현직 대통령’에 대한 체포영장 발부라는 점을 함께 언급합니다. 또...