"분기 매출 1,000억 원 돌파와 영업이익률 66%라는 경이로운 실적 축포가 터진 날, 주가는 거꾸로 16% 폭락했습니다. 미국 정부의 약가 규제 발표와 유럽 특허 소송이라는 이중의 암초를 만난 코스닥 시총 1위 알테오젠의 진짜 기업가치와 시장의 오해를 명쾌하게 팩트체크합니다."
신승엽 경제·바이오 전문기자|2026. 11. 11. 00:55 송고
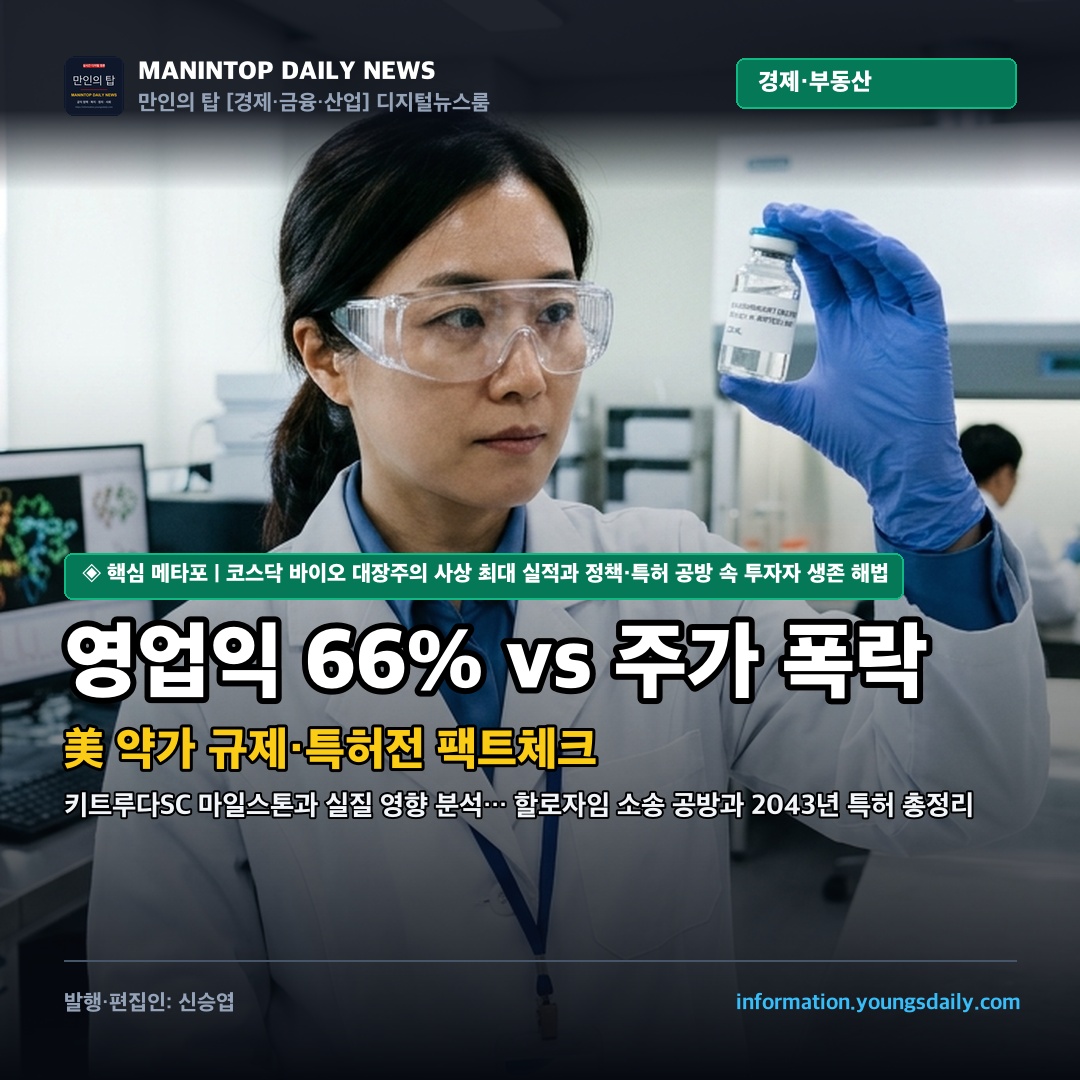
▲ 공식 보도사진 — 국내 최첨단 바이오텍 연구소에서 연구원이 독자적인 인간 히알루로니다제 효소 제형 바이알을 들어 올려 정밀 순도를 확인하고 있다. 분기 영업이익률 66%라는 역대급 실적 발표 직후 미국 정부의 약가 규제와 유럽 특허전이 겹치며 주가가 요동치고 있다.
핵심 취재 팩트 요약
알테오젠은 3분기 매출 1,198억 원(+144%), 영업이익 789억 원(+196%), 영업이익률 65.9%를 달성해 연구개발 바이오텍에서 고수익 상업화 기업으로의 완벽한 체질 개선을 입증했습니다.
미국 CMS의 약가협상 피하주사 편입 규정은 2028년까지 최대 10억 달러의 판매 마일스톤을 받는 알테오젠의 단기 실적에 영향이 없으며, 2029년 이후 로열티 구간에서도 메디케어 비중은 5~6%에 불과합니다.
할로자임과의 유럽 특허 분쟁은 머크의 즉각 항소와 영국·미국 선례로 반전 가능성이 열려 있으며, 할로자임의 2027년 특허 만료와 달리 알테오젠은 2043년까지 장기 독점 특허 방어벽을 구축하고 있습니다.
코스닥 시가총액 1위 바이오 대장주인 알테오젠이 창사 이래 최초로 분기 영업익 66%라는 경이로운 실적을 발표했음에도 주가가 하루 만에 16% 폭락하는 극심한 변동성을 겪은 가운데, 미국 정부의 약가 규제 강화와 유럽 특허전의 실질적 영향을 둘러싼 팩트체크가 집중되고 있습니다.
지난 11월 9일, 여의도 증권가는 그야말로 충격에 휩싸였습니다. 연결 기준 3분기 매출이 전년 동기 대비 144% 급증한 1,198억 원, 영업이익은 196% 폭증한 789억 원을 기록하며 시장 컨센서스를 가뿐히 뛰어넘는 어닝 서프라이즈를 달성했기 때문입니다. 제조 원가가 거의 들지 않는 기술 마일스톤 수취에 힘입어 영업이익률은 무려 65.9%에 달했습니다. 그러나 축포가 터져야 할 바로 그날, 주가는 장중 24% 가까이 곤두박질치며 16.01% 급락 마감했습니다. 시가총액 수조 원이 하루 만에 증발하는 기현상이 벌어진 것입니다.
이 기이한 폭락의 배후에는 미국 보건당국의 기습적인 약가 규제 개정과 글로벌 경쟁사인 미국 할로자임과의 유럽 특허 가처분 소송이라는 대형 악재가 자리 잡고 있었습니다. 시장 참여자들 사이에서는 "이제 피하주사 기술의 약발이 다한 것 아니냐", "유럽 시장 판매가 완전히 막히는 것 아니냐"는 극단적인 공포가 확산되었습니다. 하지만 객관적인 팩트와 수치를 정밀 분석해 보면 시장의 반응이 지나치게 과장되었다는 사실이 명백히 드러납니다. 롤러코스터를 탄 알테오젠의 진짜 현주소를 하나씩 짚어보겠습니다.
1. 사상 최대 실적에 주가는 왜 16% 폭락했나? 롤러코스터 장세의 내막
알테오젠의 3분기 성적표는 대한민국 바이오 산업 역사상 손에 꼽힐 만큼 눈부셨습니다. 분기 매출이 처음으로 1,000억 원 고지를 밟았고, 789억 원에 달하는 영업이익을 올렸습니다. 불과 2년 전인 2022년과 2023년만 해도 연구개발 비용으로 수백억 원의 적자를 내던 기업이, 글로벌 상업화 궤도에 오르자마자 폭발적인 돈을 벌어들이는 수익 머신으로 완벽히 변신한 것입니다.
특히 회사의 최대 캐시카우인 머크의 면역항암제 '키트루다 큐렉스(키트루다SC)'의 활약이 돋보였습니다. 올해 4월 미국 내 전용 보험 청구코드(J-code)가 발효되면서 처방 속도가 가속화되었고, 3분기 글로벌 매출만 8억 3,000만 달러(약 1조 1,500억 원)로 전 분기 대비 79.3% 급증했습니다. 전체 키트루다 매출 중 피하주사 제형의 비중도 2분기 5.5%에서 3분기 9.7%로 두 배 가까이 수직 상승했습니다.
하지만 주식시장은 환호 대신 투매로 응답했습니다. 11월 9일 주가는 16만 8,400원까지 미끄러져 내렸습니다. 호실적은 이미 주가에 선반영되었다는 심리에 더해, 미국 메디케어 서비스센터(CMS)의 규제 발표와 네덜란드 법원의 가처분 인용 소식이 동시다발적으로 전해지며 알고리즘 매도세를 촉발했기 때문입니다. 하지만 이튿날 저가 매수세가 유입되며 17만 6,800원으로 반등하는 등 시장의 혼선은 극에 달했습니다.
실적 및 재무 지표
2023년 연간
2024년 연간
2025년 연간
2026년 3분기 (실측치)
2026년 연간 전망 (IBK)
연결 매출액
965억 원
1,029억 원
2,159억 원
1,198억 원 (+144.4%)
4,573억 원 (+111.8%)
연결 영업이익
-97억 원 (적자)
254억 원 (흑자전환)
1,069억 원
789억 원 (+195.8%)
2,958억 원 (+176.7%)
영업이익률 (OPM)
적자
24.7%
49.5%
65.9% (사상 최고)
64.7% 달성 전망
키트루다SC 매출 비중
-
-
미국 FDA 허가
전체 키트루다의 9.7%
연말 두 자릿수 비중 돌파
2. 美 CMS의 IRA 약가 규제 폭탄… 피하주사 제형 편입이 미칠 진짜 파장
투자자들이 가장 크게 동요한 첫 번째 뇌관은 미국 CMS가 발표한 인플레이션 감축법(IRA) 최종 규칙이었습니다. 핵심 골자는 오리지널 정맥주사에 효소를 섞어 만든 피하주사 복합제형도 별개의 신약이 아니라 기존 정맥주사와 동일한 약가협상 대상군으로 묶어 강제로 가격을 깎겠다는 내용이었습니다.
그동안 글로벌 제약사들은 특허 만료가 임박하면 정맥주사를 피하주사로 슬쩍 바꿔 약가 인하를 피하는 일명 '에버그리닝(Evergreening)' 전략을 구사해 왔습니다. 미국 정부가 이 꼼수를 원천 차단하겠다고 선언하면서, 키트루다SC 역시 2027년 협상 대상에 오를 경우 2029년부터 깎인 가격을 적용받게 될 처지에 놓인 것입니다.
하지만 이것이 알테오젠의 실적을 당장 갉아먹는 치명타일까요? 사실관계를 따져보면 기우에 불과합니다. 알테오젠은 현재 약을 팔 때마다 떼어주는 로열티를 받는 단계가 아니라, 누적 판매 목표를 달성할 때마다 목돈을 챙기는 '판매 마일스톤(최대 10억 달러, 약 1조 4,000억 원)' 구간에 있습니다. 이 마일스톤은 2028년까지 약가 변동과 상관없이 판매량에 따라 전액 입금됩니다. 약가 인하가 적용되는 2029년 이후 로열티(순매출의 약 2%)를 받을 때도, 미국 내 키트루다 처방의 94% 이상은 약가 인하와 무관한 사보험 시장에서 발생합니다. 정부 공보험(메디케어) 비중은 고작 5~6%에 불과해 실질적인 타격은 한 자릿수 초반에 그칩니다.
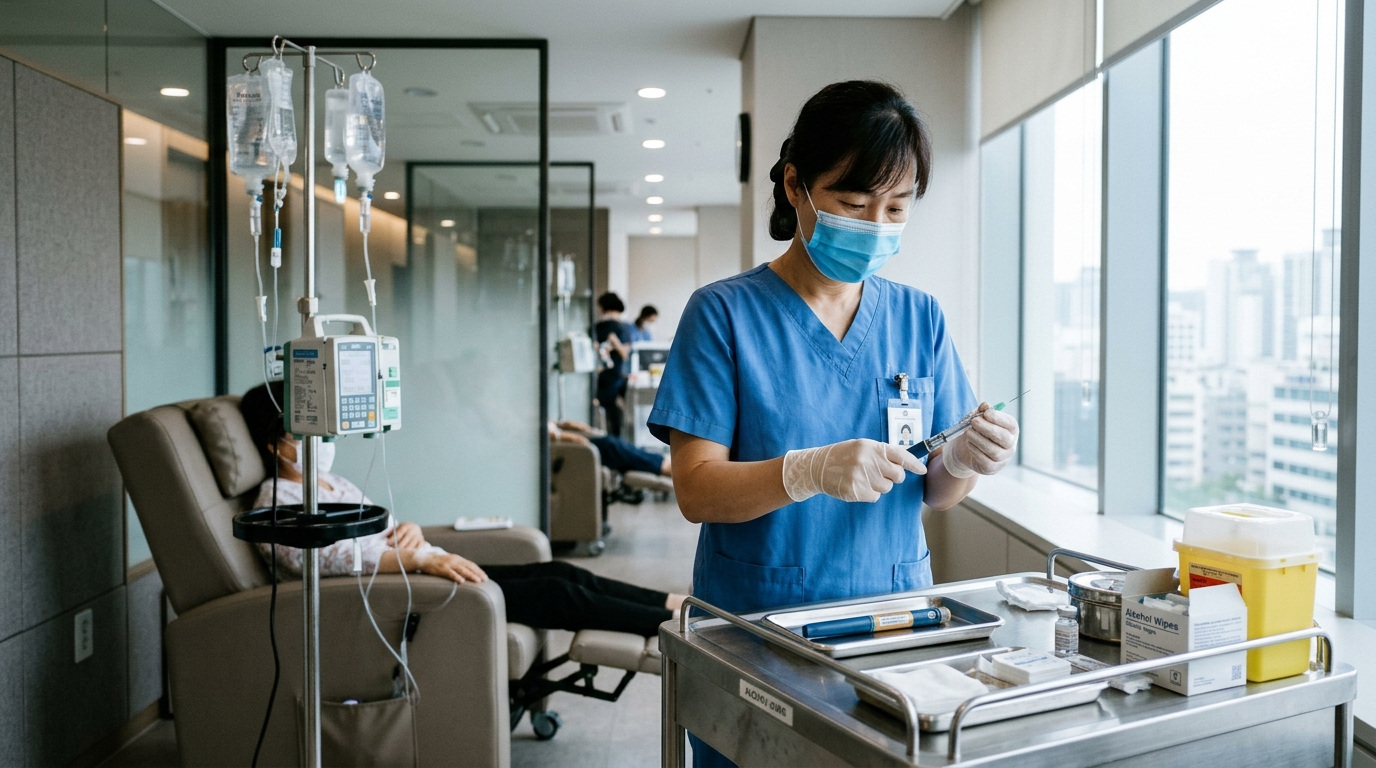
▲ 의료 현장 보도사진 — 서울 시내 대형병원 암센터 주사실에서 간호사가 신속 투여가 가능한 피하주사(SC) 주사기를 준비하고 있다. 몇 시간 동안 링거를 꽂고 누워 있어야 했던 기존 정맥주사(IV)와 달리 단 1~2분 만에 투약이 완료되어 환자의 고통을 줄이고 병원 병상 회전율을 3배 이상 끌어올린다.
3. '독점 2강' 美 할로자임과의 글로벌 특허전… 네덜란드 가처분과 2043년 방어벽
두 번째 공포는 전 세계 피하주사 시장을 독점하고 있는 미국 할로자임 테라퓨틱스와의 법적 전쟁입니다. 할로자임은 머크의 키트루다SC가 자사의 유럽 개량 히알루로니다제 특허(EP622)를 침해했다며 네덜란드 법원에 제조 및 판매 금지 가처분 소송을 제기했고, 지난 10월 7일 법원이 이를 인용했습니다. 네덜란드가 머크의 유럽 내 핵심 물류 거점이다 보니 유럽 공급망이 셧다운되는 것 아니냐는 공포가 주가를 짓눌렀습니다.
그러나 이 판결은 본안 소송 전의 1심 잠정 가처분 결정일 뿐이며, 머크는 즉시 상급법원에 항소했습니다. 다른 국가들의 법적 판단을 살펴보면 분위기는 정반대입니다. 영국 법원에서는 할로자임이 자사의 실험적 데이터가 턱없이 부족하다는 점을 시인하고 스스로 특허 권리를 취소하며 소송을 포기했습니다. 미국 특허심판원(PTAB) 역시 할로자임의 핵심 특허에 대해 무효 결정을 내리며 머크와 알테오젠의 손을 들어준 전례가 있습니다.
가장 본질적인 승부처는 특허의 수명입니다. 할로자임의 핵심 미국 물질특허는 당장 내년인 2027년에 만료되어 '특허 절벽'에 직면합니다. 반면 알테오젠의 ALT-B4 원천 물질특허는 2043년까지 살아 숨 쉽니다. 단백질 구조의 열안정성도 뛰어나고 환자 체내 항체 형성 부작용(면역원성)도 훨씬 낮습니다. 2027년 이후 복제약(바이오시밀러)의 공세를 막아내야 하는 글로벌 빅파마 입장에서는 2043년까지 독점권이 보장되는 알테오젠이 유일한 동아줄인 셈입니다.
기술 및 특허 비교 지표
알테오젠 (ALT-B4 / Hybrozyme)
할로자임 (rHuPH20 / ENHANZE)
글로벌 시장 경쟁력 분석
미국 핵심 물질특허 만료
2043년 초까지 존속 (장기 독점 보장)
2027년 만료 예정 (특허 절벽 직면)
알테오젠이 향후 15년 이상 독점적 지배력 행사
유럽 핵심 특허 만료
2040년대까지 존속
2029년 만료 예정
유럽 시장에서도 알테오젠의 특허 수명이 압도적
단백질 열안정성
체온 및 고온에서도 효소 활성 완벽 유지
열에 취약하여 제조·유통·보관 시 제약
공정 수율과 생산 원가 측면에서 알테오젠 우위
면역원성 (부작용)
300개 이상 변이체 설계로 항체 형성 최소화
반복 투여 시 체내 중화항체 발생 우려 상존
만성 질환 치료제 장기 투약 시 안전성 확보
적용 플랫폼 영역
단일항체, 면역항암제, ADC, AOC 확장
기존 단일항체 및 면역항암제 위주
엔허투 등 차세대 신약 모달리티 확장성 독점
4. 정맥 링거를 2분 만에 끝낸다… 하이브로자임(ALT-B4) 기술력과 경제적 효용
알테오젠의 기술이 수조 원의 가치를 인정받는 이유는 사람의 몸과 병원 시스템을 바꾸는 혁신성에 있습니다. 피부 아래 피하조직에는 '히알루론산'이라는 천연 물질이 물을 머금고 젤리 같은 그물망 장벽을 치고 있습니다. 이 때문에 암 치료제 같은 거대한 단백질 약물을 피하주사로 넣으면 약이 퍼지지 못하고 극심한 통증을 유발합니다. 암 환자들이 병원에 가 몇 시간씩 링거 주삿바늘을 꽂고 누워 있어야 했던 이유입니다.
알테오젠의 '하이브로자임(ALT-B4)'은 이 젤리 장벽을 일시적으로 사르르 녹여 약물이 혈관 속으로 빠르게 흡수되도록 길을 열어주는 기적의 효소입니다. 약물이 다 흡수되고 나면 히알루론산은 며칠 안에 원래대로 다시 복구됩니다.
이 효소가 가져온 변화는 눈부십니다. 병원 침대에 누워 30분에서 최대 3시간 동안 맞아야 했던 항암 주사가 단 1~2분 만에 팔이나 배에 찌르는 주사 한 대로 끝납니다. 유방암 치료제 트라스투주맙의 경우 환자가 주사실 의자에 머무는 시간(Chair time)이 84분에서 22분으로 무려 62분이나 줄었습니다. 병원 입장에서는 간호 인력의 부담이 줄고 주사실 침대 회전율이 3배 이상 뛰게 됩니다. 환자는 고통에서 해방되고 병원은 진료 효율이 극대화되니, 전 세계 병원과 환자들이 피하주사 제형을 선택하지 않을 이유가 없습니다.
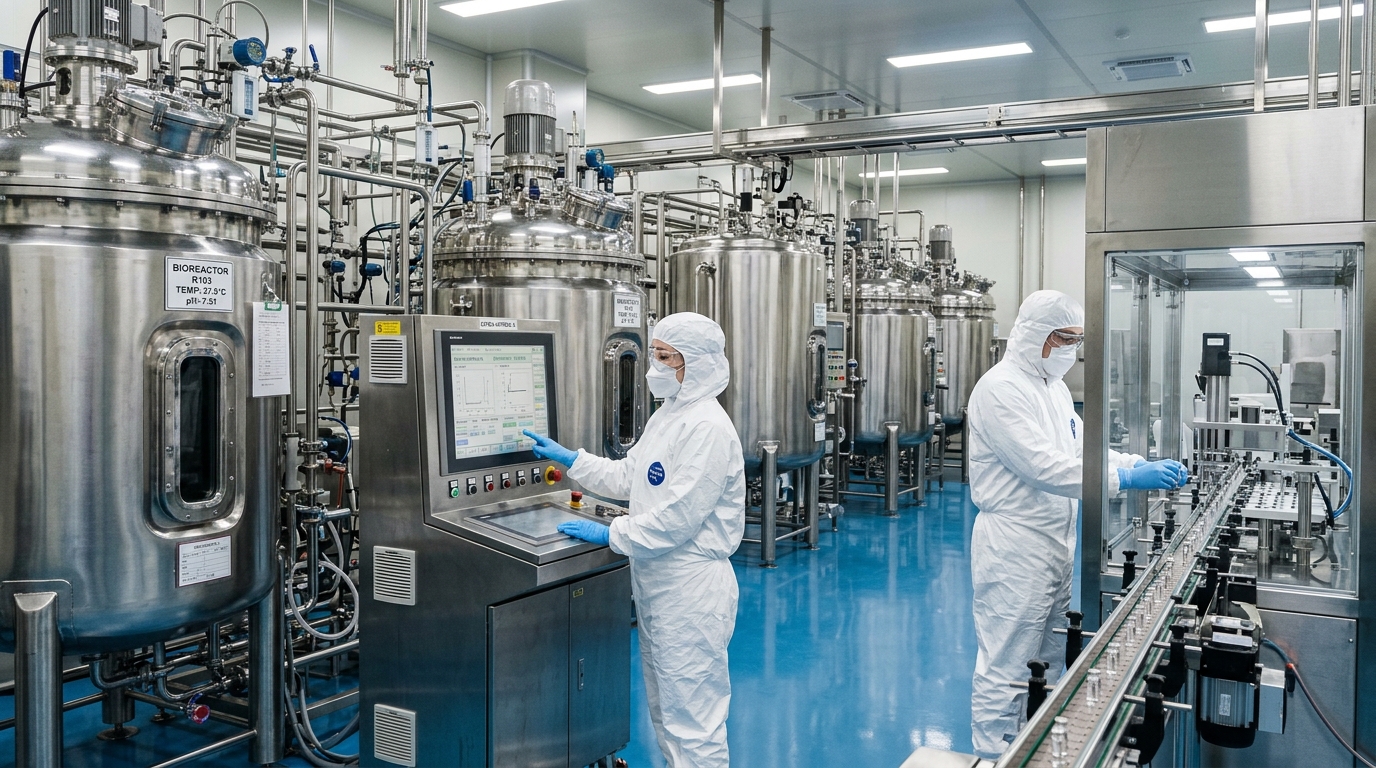
▲ 첨단 생산 인프라 보도사진 — 최첨단 바이오의약품 cGMP 공장에서 공정 엔지니어들이 대형 배양기와 무균 주사제 충전 라인을 가동하고 있다. 알테오젠은 2028년까지 2,532억 원을 투입해 자체 생산 설비를 내재화하며 단순 연구개발 기업을 넘어 종합 바이오 제약사로 도약하고 있다.
5. 누적 14조 원 기술수출과 10대 파트너십… 머크부터 엔허투 ADC·노바티스까지
알테오젠을 둘러싼 가장 큰 오해 중 하나는 "키트루다 하나에만 기대는 외나무다리 기업"이라는 시선입니다. 하지만 실제 수주 잔고를 들여다보면 알테오젠의 영토는 이미 글로벌 빅파마 10곳으로 거대하게 확장되어 있습니다. 누적 기술수출 계약 규모만 14조 원(약 119억 달러)에 달하며, 특히 2026년 올해에만 성사시킨 신규 빅딜만 4건, 금액으로는 6조 원(44억 5,000만 달러)을 돌파했습니다.
지난 1월 영국 GSK와의 젬퍼리 계약을 시작으로, 3월 미국 바이오젠, 8월 글로벌 빅파마와의 비공개 계약이 연달아 터졌습니다. 특히 9월에는 스위스 노바티스와 최대 32억 2,300만 달러(약 4조 5,000억 원)에 달하는 역대 최대 규모의 복수 의약품 독점 라이선스 계약을 체결하며 업계를 경악시켰습니다.
더욱 주목해야 할 대목은 '꿈의 항암제'라 불리는 차세대 모달리티로의 확장입니다. 알테오젠은 일본 다이이찌산쿄와 손잡고 전 세계 1위 항암 치료제인 '엔허투(Enhertu)'의 피하주사 제형 개발을 세계 최초로 진행하고 있습니다. 세포독성 항암제를 항체에 붙여 암세포만 정밀 타격하는 ADC 약물은 정맥주사 시 약물이 혈관에 너무 빨리 퍼져 부작용 관리가 난제였습니다. 피하주사로 투여할 경우 천천히 흡수되어 독성은 크게 줄이고 약효는 온전히 유지할 수 있습니다. 엔허투SC 임상이 성공할 경우, 글로벌 제약사들이 보유한 수백 개의 ADC 파이프라인이 줄줄이 알테오젠 문을 두드릴 수밖에 없는 구조적 생태계가 열리고 있습니다.
6. 테르가제와 2,532억 원 생산 내재화… 증권가 목표주가와 투자자 팩트체크
알테오젠은 남의 약에 효소를 섞어주는 기술용역 회사에 머무르지 않고 있습니다. 자체 신약과 바이오시밀러를 직접 만들어 파는 종합 제약사로의 진화를 착착 진행 중입니다. 지난해 식약처 허가를 받아 시판 중인 '테르가제(ALT-BB4)'는 기존 소나 양의 고환에서 짜내던 동물성 제품의 알레르기 부작용을 원천 차단한 재조합 완제의약품으로 성형외과와 정형외과 등에서 독점적 입지를 굳히고 있습니다. 여기에 아일리아 바이오시밀러(아이럭스비/아이젠피)의 유럽 및 국내 허가를 획득해 상업 판매를 시작했습니다.
기업의 그릇도 완전히 바뀝니다. 오는 12월 30일을 기점으로 바이오시밀러 자회사인 알테오젠바이오로직스를 전격 흡수합병합니다. 2028년까지 2,532억 원을 쏟아부어 의약품 원료와 완제품을 자체 공장에서 직접 생산하는 cGMP 생산 라인을 완공할 계획입니다. 기술료만 받던 회사에서 직접 생산하고 유통해 마진을 극대화하는 수직계열화가 완성되는 것입니다.
주요 증권사 리서치센터들은 단기적인 규제 노이즈에도 불구하고 알테오젠의 본질 가치는 흔들림이 없다고 평가합니다. IBK투자증권은 약가 인하 가능성을 보수적으로 반영해 목표주가를 32만 원으로 조정하면서도 확고한 '매수' 의견을 유지했고, 신한투자증권은 43만 원, 대신증권은 45만 원을 유지했습니다. 일시적인 뉴스에 흔들려 투매에 동참하기보다는 2043년까지 이어질 장기 독점력과 10대 빅파마 파이프라인의 임상 진척을 냉정하게 바라보는 안목이 필요한 시점입니다.
관할 사법 법원
소송 핵심 쟁점 및 진행 경과
현 시점 법적 효력 및 파급 영향
향후 반전 가능성 및 전망
네덜란드 법원
유럽 특허 EP622 침해 가처분 (10월 7일)
유럽 8개국 내 키트루다SC 제조·판매 금지 명령
머크 즉각 항소 완료, 본안 소송 전 잠정 처분
영국 법원
할로자임 특허 권리 범위 및 유효성 다툼
할로자임, 실험 근거 부족으로 특허 자진 취소
머크와 알테오젠의 기술적 정당성 입증 선례
미국 특허심판원 (PTAB)
할로자임 MDASE 핵심 특허 무효 심판
특허심판원, 할로자임 일부 핵심 특허 무효 결정
미국 내 특허 침해 리스크 원천 무력화 선례 확보
이탈리아 법원
머크 자회사 및 위탁제조사 상대 가처분
2026년 12월 2일 첫 심리 예정
유럽 생산 거점 추가 제한 여부 판가름 관전 포인트
In-Depth InvestigationEconomy & Real Estate
[In-Depth Analysis] Record 66% Operating Margin vs Sudden 16% Plunge: Fact-Checking Alteogen Amid US Drug Pricing Curbs and Patent Feuds
"On the very day Alteogen posted an astonishing 66 percent operating margin and crossed 100 billion won in quarterly revenue, shares plummeted 16 percent. Navigating the crosscurrents of United States drug pricing mandates and a European patent crossfire with Halozyme, this report provides a rigorous fact-check of Korea's premier biotech leader."
▲ Official Press Photo — A senior biopharmaceutical scientist in an advanced research laboratory inspects a vial containing human recombinant hyaluronidase solution. Following record third-quarter earnings exceeding a 65 percent operating margin, US policy announcements and European patent disputes triggered intense market volatility.
Executive Fact Briefing
Alteogen delivered third-quarter revenue of 119.8 billion won (+144%) and operating profit of 78.9 billion won (+196%), posting a record 65.9% margin to confirm its transformation into a high-margin commercial power.
The United States CMS Inflation Reduction Act pricing rules carry zero impact on commercial sales milestones through 2028, and Medicare represents merely 5 to 6 percent of US Keytruda revenue during subsequent royalty phases.
While a Dutch court issued a preliminary injunction, Halozyme previously withdrew claims in the UK and faced patent invalidations before the US PTAB, while Alteogen holds exclusive global patent protection extending to 2043.
South Korea's leading biopharmaceutical enterprise Alteogen generated an extraordinary 65.9 percent operating profit margin on record quarterly revenue, yet experienced a sudden 16 percent equity plunge as investors grappled with United States drug pricing rules and European patent litigation.
On November 9, domestic equity markets were rattled by an apparent paradox. Alteogen unveiled third-quarter consolidated revenue surging 144 percent year-over-year to 119.8 billion won, while operating profit escalated 196 percent to 78.9 billion won, comfortably eclipsing market consensus. Backed by licensing milestones carrying minimal manufacturing friction, operating margins reached an unprecedented 65.9 percent. However, rather than rallying, the stock tumbled as much as 23.9 percent intraday before closing down 16.01 percent, erasing trillions of won in market capitalization in a single trading session.
The violent dislocation stemmed from two macro headwinds: final Inflation Reduction Act guidelines from the United States Centers for Medicare and Medicaid Services (CMS) encompassing subcutaneous reformulations, and a preliminary injunction granted by a Dutch court in favor of rival Halozyme Therapeutics. Speculative fears that the subcutaneous delivery thesis had collapsed quickly engulfed market commentary. However, a rigorous examination of contractual milestones, legal precedents, and structural patent longevity demonstrates that market anxieties have dramatically overstated operational risks. Here is an exhaustive analysis of Alteogen's technological and financial standing.
1. Why Did Shares Plunge 16% Despite Record Earnings? Inside the Market Rollercoaster
Alteogen's third-quarter financial report established a landmark operational transition for the Korean biopharmaceutical sector. For the first time in its corporate history, quarterly revenue crossed the 100 billion won threshold. Having absorbed extensive clinical research deficits across 2022 and 2023, the enterprise demonstrated the immense operating leverage unlocked when proprietary platforms enter full-scale global commercialization.
Performance was propelled by commercial expansion of Merck's Keytruda Qlex, the subcutaneous formulation enabled by Alteogen's recombinant enzyme. Following the activation of a dedicated J-code reimbursement mechanism in the United States in April, prescription velocity accelerated. Global third-quarter sales reached 830 million dollars, jumping 79.3 percent from the preceding quarter. Subcutaneous formulations expanded from 5.5 percent of total Keytruda revenue in the second quarter to 9.7 percent in the third quarter.
Nonetheless, financial markets reacted with rapid liquidation. Closing at 168,400 won, shares were impacted by algorithmic trading triggered by contemporaneous policy releases from Washington and legal headlines from Amsterdam. When trading resumed the following morning, institutional dip-buying restored prices to 176,800 won, highlighting the intense ongoing battle between fundamental cash generation and headline regulatory risks.
Financial Metric (KRW)
FY2023 Audited
FY2024 Audited
FY2025 Audited
3Q2026 Verified Actual
FY2026 Consensus (IBK)
Consolidated Revenue
96.5 Billion Won
102.9 Billion Won
215.9 Billion Won
119.8 Billion Won (+144%)
457.3 Billion Won (+112%)
Operating Profit
-9.7 Billion Won (Loss)
25.4 Billion Won (Profit)
106.9 Billion Won
78.9 Billion Won (+196%)
295.8 Billion Won (+177%)
Operating Margin
Operating Loss
24.7%
49.5%
65.9% (Historic High)
64.7% Full-Year Target
Keytruda SC Revenue Share
Development Phase
Commercial Preparation
FDA Approval Achieved
9.7% of Global Volume
Double-Digit Share Targeted
2. The US CMS IRA Drug Pricing Rule: What the Subcutaneous Expansion Really Means
The primary driver of retail investor anxiety was the publication of final guidance under the Inflation Reduction Act by the United States CMS. Regulators determined that subcutaneous combination products created by adding hyaluronidase enzymes to existing intravenous biologics will be classified alongside original intravenous formulations for federal price negotiation purposes.
Historically, global pharmaceutical companies countered imminent patent expiries by transitioning intravenous franchises to subcutaneous delivery, extending exclusivity through product lifecycle enhancements. With Washington seeking to close this regulatory pathway, Keytruda SC faces mandatory negotiated pricing by 2029 if the primary intravenous formulation is selected for federal negotiations in 2027.
However, this regulatory adjustment does not undermine Alteogen's medium-term cash trajectory. The company is currently operating under a commercial sales milestone framework totaling up to 1.0 billion dollars through 2028, which depends on aggregate clinical adoption rather than statutory unit pricing. Furthermore, when net commercial royalties (approximately 2 percent) commence after 2029, United States public Medicare exposure accounts for merely 5 to 6 percent of aggregate Keytruda oncology billing. Over 94 percent of volume originates within private commercial insurance plans unaffected by CMS negotiations, rendering the net revenue impact marginal.
▲ Clinical Treatment Photography — An oncology nurse prepares a pre-filled subcutaneous syringe in a clinical outpatient infusion center. By compressing multi-hour intravenous drips into a simple one-to-two-minute subcutaneous injection, the formulation mitigates patient discomfort while tripling clinic infusion chair turnover.
3. The Global Patent Feud With Halozyme: Dutch Injunction Realities and the 2043 Defense
The secondary headwind involves intense legal maneuvering by sole global competitor Halozyme Therapeutics. Halozyme alleged that Keytruda SC infringes its European patent EP622 covering modified hyaluronidase variants, securing a preliminary injunction from the District Court of The Hague on October 7 restricting distribution across eight European jurisdictions. Given the Netherlands' role as Merck's primary European packaging hub, investors feared widespread logistics disruption.
Crucially, this ruling represents an interlocutory order subject to immediate appeal. Precedents across other jurisdictions indicate substantial vulnerability in Halozyme's claims. In parallel proceedings before the High Court of England and Wales, Halozyme voluntarily revoked its EP622 patent rights after admitting evidentiary deficiencies in its experimental data. In the United States, the Patent Trial and Appeal Board (PTAB) previously declared key Halozyme enzyme patents invalid, providing strong legal support for Merck's appellate strategy.
More importantly, fundamental patent longevity strongly favors Alteogen. Halozyme's core composition of matter patents in the United States expire in early 2027, creating an imminent patent cliff. Conversely, Alteogen's foundational ALT-B4 composition patents maintain ironclad legal protection through early 2043. Featuring superior thermal stability and lower immunogenicity profiles, Alteogen stands as the sole long-term partner capable of shielding global blockbusters against biosimilar competition over the next two decades.
Platform Comparison Metric
Alteogen (ALT-B4 / Hybrozyme)
Halozyme (rHuPH20 / ENHANZE)
Global Strategic Implication
US Composition Patent Expiry
Active Until Early 2043 (Long Exclusivity)
Expires Early 2027 (Impending Cliff)
Alteogen controls unmatched exclusivity for 15+ years
European Patent Duration
Secured Into 2040s
Expires 2029
Ensures European commercial longevity past 2030
Enzyme Thermal Stability
Maintains complete activity at elevated heat
Vulnerable to thermal degradation during handling
Lowers cold-chain shipping and manufacturing costs
Immunogenicity Profile
Engineered across 300+ mutations to curb antibodies
Persistent anti-drug antibody formation risks
Essential for repeated chronic disease administration
Application Scope
Monoclonal Antibodies, ADCs, AOCs, Bispecifics
Conventional monoclonal and checkpoint inhibitors
Exclusively positioned to capture next-gen oncology formats
4. Slashing Multi-Hour IVs to 2 Minutes: Hybrozyme Technology and Clinical Economics
The multi-billion-dollar valuation assigned to Alteogen's platform originates from its transformative clinical and health economic utility. Human subcutaneous tissue contains extracellular hyaluronan, a naturally occurring polysaccharide forming a dense, gel-like barrier that prevents the rapid systemic uptake of large-molecule therapeutic proteins. Consequently, oncology biologics have historically required lengthy intravenous administration.
Alteogen's proprietary Hybrozyme platform utilizes engineered recombinant human hyaluronidase (ALT-B4) to temporarily hydrolyze this interstitial matrix, creating transient fluid channels that allow rapid subcutaneous absorption. Within days of injection, the localized tissue barrier regenerates naturally.
This biological mechanism transforms hospital economics. Treatments that once required 30 to 180 minutes of continuous intravenous chair time are administered in under two minutes via pre-filled syringes. In trastuzumab clinical studies, average patient infusion chair time declined from 84.3 minutes to 22.5 minutes, freeing up critical hospital infrastructure and expanding day-clinic throughput threefold. For healthcare systems and patients alike, subcutaneous convenience represents an irreversible standard of care.
▲ Advanced Manufacturing Photo — Process engineers supervise automated fermentation bioreactors and sterile fill-finish operations inside a cGMP biomanufacturing facility. Alteogen is deploying 253.2 billion won through 2028 to internalize clinical and commercial supply chains, evolving into a fully integrated pharmaceutical powerhouse.
5. 14 Trillion Won in Licensing Deals Across 10 Partners: From Merck to Enhertu and Novartis
A frequent market misconception portrays Alteogen as entirely dependent on a single partnership. In reality, the enterprise has constructed a broad portfolio encompassing ten multinational pharmaceutical leaders. Cumulative out-licensing commitments exceed 14 trillion won (11.9 billion dollars), with four mega-agreements finalized in 2026 alone generating 4.45 billion dollars in transaction value.
Following agreements with GSK and Biogen early in the year, Alteogen secured an unprecedented multi-target licensing contract with Novartis in September valued at up to 3.22 billion dollars. This agreement grants exclusive options across undisclosed therapeutic assets, cementing Alteogen's standing among elite European pharmaceutical developers.
Crucially, the platform is pioneering transitions beyond standard monoclonal antibodies into complex modalities. Through a landmark alliance with Daiichi Sankyo, Alteogen is executing the world's first subcutaneous reformulation of an antibody-drug conjugate (ADC), the marquee therapy Enhertu. While intravenous ADC administration carries systemic toxicity risks from sudden peak blood concentrations, subcutaneous delivery flattens pharmacokinetic curves, reducing adverse events while preserving therapeutic efficacy. Success in this trial will unlock access to dozens of global ADC pipelines.
6. Tergase Commercialization and 253.2B Won cGMP Facilities: Wall Street Targets and Fact Sheet
Alteogen is concurrently executing a vertical integration strategy to transcend licensing royalties and establish autonomous manufacturing capabilities. Its proprietary product Tergase (ALT-BB4), a pure recombinant hyaluronidase approved by Korean regulators in 2024, is actively gaining market share across surgical and aesthetic clinics by eliminating animal-derived bovine impurities. Furthermore, biosimilar programs including Eyluxvi (aflibercept) have secured marketing authorizations across European and domestic jurisdictions.
On December 30, Alteogen will finalize the complete absorption of its clinical development subsidiary Alteogen Biologics, consolidating research, regulatory affairs, and manufacturing. Between 2026 and 2028, the company is deploying 253.2 billion won to erect dedicated cGMP drug substance and drug product facilities, internalizing higher manufacturing margins.
Major equity research institutions conclude that underlying asset value remains firmly intact despite regulatory noise. IBK Securities maintained a buy recommendation with a conservative 320,000 won price target factoring in potential pricing adjustments, while Shinhan Securities targets 430,000 won and Daishin Securities projects 450,000 won. Supported by 2043 patent protection and expanding global partnerships, institutional consensus affirms that current valuations represent a compelling structural entry point.
Jurisdiction and Legal Venue
Core Dispute and Procedural Trajectory
Immediate Legal Status and Market Reach
Appellate Prospects and Judicial Analysis
District Court of The Hague
Preliminary injunction regarding EP622 (Oct 7)
Preliminary injunction across eight EU territories
Merck filed immediate appeal; merits case remains open
1월이 시작되면 감기는 이미 우리 곁에 와 있습니다. 2월, 3월, 4월까지 이어지는 추위와 건조함은 코와 목을 가장 먼저 공격합니다. 아침에 일어나자마자 막혀 있는 코. 계속 흐르는 콧물. 괜히 칼칼해지는 목. 이 증상은 “시작”일 뿐입니다. 한 번 무너지면 일주일, 길면 한 달까지 끌고 갑니다. 약을 먹으면 잠깐 괜찮아집니다. 하지만 며칠 뒤 또 반복됩니다. 왜일까요? 감기는 ‘치료’의 문제가 아니라 ‘관리’의 문제이기 때문입니다. 대부분은 감기가 오고 나서 약을 찾습니다. 하지만 진짜 중요한 건 감기가 오기 전에 코와 목을 지키는 것입니다. 건조한 실내 공기, 차가운 바깥 공기, 눈에 보이지 않는 세균. 코와 목은 매일 공격받고 있습니다. 지긋지긋하죠! 그런데도 우리는 아무 준비 없이 버티고 있습니다. 이번 겨울도 그렇게 보낼 건가요? 사실 방법은 어렵지 않습니다. 코를 깨끗하게 관리하고, 목을 따뜻하게 보호하고, 점막을 촉촉하게 유지하고, 기관지를 미리 관리하고, 외부 공기를 차단하는 것. 이 다섯 가지만 꾸준히 해도 감기약 없이 겨울을 보내는 것이 충분히 가능합니다. 🔥 이제부터 그 방법을 하나씩 살펴보겠습니다. 🔥 1. 코와 목을 먼저 관리해야 하는 과학적 이유 감기의 대부분은 코 점막에서 시작됩니다. 국제 학술지 Nature Reviews Microbiology 와 Journal of Allergy and Clinical Immunology 에 실린 호흡기 감염 관련 연구들에서는, 감기 바이러스가 비강 상피세포에 먼저 부착해 증식한다는 점을 설명하고 ...
리모델링사업이 진행 중인 아파트를 매매할 때 “계약금 10%를 언제까지 내야 하느냐”는 질문이 특히 많이 나옵니다. 이주공고(이주 안내)가 7~11월쯤이라고 들으면, 그 시점에 맞춰 계약금도 움직일 것 같아서 더 헷갈리기 쉽습니다. 하지만 실제 납부기한은 ‘이주공고가 언제냐’만으로 자동 결정되지 않는 경우가 많습니다. 1) 계약금 10% 납부기한: 결국 ‘문서에 적힌 일정’이 기준 계약금 10%를 언제까지 납부해야 하는지는, 내가 서명하는 매매계약서(특약 포함) 와 사업주체/조합이 제시한 공고·안내문 에 적힌 납부 일정이 기준이 됩니다. 실제 공고문에서는 분양대금 납부의 큰 틀(계약금→중도금→잔금)을 먼저 안내하고, 상세 일정은 별도 표나 유의사항으로 제시하는 방식이 흔합니다. 또, 계약서 문구에 따라 지급 시점이 조건부로 설정될 수도 있습니다. 예를 들어 한 사례 소개 자료에서는 용역계약서에 잔금(10%) 지급시기가 “사업승인 후”로 기재되어 있었다는 점이 언급됩니다. 이런 식으로 ‘사업 단계’와 지급을 연동하는 문구가 들어가면, 질문의 답은 계약서 문구를 확인해야만 확정됩니다. 관련 내용은 링크 에서 문구 사례를 확인할 수 있습니다. 2) 입주자모집공고에서 확인되는 ‘납부 순서’와 잔금 마감 시점 공고문에 적힌 문구를 보면, 납부 순서와 잔금 마감에 대한 기준이 비교적 명확하게 제시되는 경우가 있습니다. 예를 들어 한 입주자모집공고에는 “분양금액(주택가격)은 계약금, 중도금, 잔금의 순서로 납부”하며 “잔금은 입주(열쇠 수령일) 전에 완납”해야 한다고 안내되어 있습니다. (문구 확인: 링크 ) 이 문구가 의미하는 바는 최소 2가지입니다. 분양/공급 형태의 문서에서는 ‘계약금→중도금→잔금’ 흐름이 공식적으로 안내될 수 있습니다. 잔금은 “입주(열쇠 수령)” 이전에 완납해야 한다는 마감 기준이 문서에 적혀 있을 수 있습니다. 다만, 위 공고문 문구는 잔금 마감에 대한 기준을 보여주지만, 계약금 10%의...
윤석열 전 대통령 탄핵 인용 소식을 접하면, 가장 궁금한 지점은 ‘헌재가 정확히 무엇을 위헌·위법으로 봤는가’입니다. 또한 탄핵과 별개로 진행되는 형사재판(내란 우두머리 혐의 등)이 어디까지 왔는지도 함께 정리할 필요가 있습니다. 아래 내용은 제공된 기사/게시물 스니펫과 링크에서 확인되는 범위만 모아, 일반인이 흐름을 이해하기 쉽게 정리한 것입니다. 1) 탄핵 인용 관련: 스니펫에서 확인되는 ‘판단의 골격’ 제공된 근거 중 조국혁신당 사이트에는 헌법재판소가 윤석열 탄핵 심판에서 “피청구인의 위헌·위법행위는 국민 신임 …”이라는 취지로 판단했다는 문장이 인용돼 있습니다( 링크 ). 이 인용문만 놓고 보면, ‘위헌·위법행위’가 있었는지와 그로 인해 ‘국민의 신임’이 어떻게 평가됐는지가 핵심 축으로 소개됩니다. 다만 질문에서 요청하신 세부 항목, 즉 비상계엄 선포 자체를 문제 삼은 구체적 이유, 계엄 이후 조치(포고령, 국회 통제 등)의 어떤 지점이 헌법 위반인지, 국회의 권한행사 방해 및 정치활동 제약을 어떤 논리로 판단했는지 등은, 이번에 제공된 근거의 제목/스니펫만으로는 조항·사실관계·판단 구조가 그대로 제시돼 있지 않습니다. 따라서 이 글에서는 ‘헌재가 무엇을 문제 삼았다’는 세부 리스트를 단정적으로 재구성하기보다, 현재 확인 가능한 문구 수준의 요약(위헌·위법행위 → 국민 신임의 문제로 평가)까지만 적습니다. 만약 헌재 결정문 전문(주문 및 이유)이 추가로 확인되면, 그때는 문장 단위로 ‘어떤 행위’와 ‘어떤 헌법 원리/조항’이 연결되는지(예: 권력분립, 국회의 권한, 정치적 기본권 등) 구조화해 정리하는 것이 가장 정확합니다. 2) 형사 절차(내란 혐의) 관련: 체포영장과 1심 선고 언급 탄핵 심판과 별도로, 12·3 비상계엄 사태로 내란 혐의를 받는 윤석열 대통령에 대해 2024년 12월 31일 체포 영장이 발부됐다는 BBC 보도가 있습니다( 링크 ). 해당 보도는 ‘현직 대통령’에 대한 체포영장 발부라는 점을 함께 언급합니다. 또...