2026 청년미래적금 완전정복: 가입 조건 3대 축부터 8% 금리·도약계좌 갈아타기 실익 총정리
만인의 탑 편집국11월 16, 2026
▲ 2026 청년미래적금 완전정복: 가입 조건 3대 축부터 8% 금리·도약계좌 갈아타기 실익 총정리 (공식 보도 자료)
📌 핵심 브리핑 · 주요 쟁점 및 핵심 요약
청년층의 자산 형성을 가로막던 장기 납입의 부담을 덜고 실질적인 종잣돈 마련을 돕기 위해 2026년 6월 출범한 청년미래적금이 2030 세대의 폭발적인 관심을 모으고 있습니다. 기존 청년도약계좌의 5년 만기를 현실적인 3년으로 대폭 단축하고 월 최대 50만 원 자유적립식으로 설계된 이 상품은 최고 연 8.0%의 파격적인 고금리와 본인 납입액의 최대 12%에 달하는 정부기여금, 그리고 15.4% 전액 비과세 혜택을 결합하여 일반 적금 기준 세전 연 19.4%라는 경이로운 환산 수익률을 제공합니다. 만 19~34세(군 복무 시 최대 만 40세) 연령 기준과 2025년 총급여 7,500만 원 이하 소득 요건, 신혼부부 2인 맞벌이 기준 중위소득 250% 완화 특례부터 14개 은행별 우대금리 공략법, 그리고 기존 청년도약계좌 가입자가 놓쳐서는 안 될 선 개설 후 특별해지 갈아타기 실익까지 청년 금융 소비자를 위한 핵심 쟁점을 총정리합니다.
SPONSORED · ADVERTISEMENT
1. 3년 만기 단축과 청년미래적금 출범 배경 및 청년 부채 현실
사회에 첫발을 내딛는 청년들이 마주한 현실적인 경제 지표는 해가 갈수록 매서워지고 있습니다. 통계청과 관계 부처의 청년 삶 실태조사에 따르면 만 19세부터 34세 청년들의 연평균 소득은 2,625만 원 수준에 머물러 있는 반면, 평균 부채는 1,637만 원으로 최근 2년 사이에만 40% 가까이 치솟았습니다. 특히 청년 부채의 70% 이상이 주거 마련 채무에 묶여 있어 가파른 금리 인상과 집값 변동의 충격파를 온몸으로 받아내고 있는 실정입니다.
이러한 청년층의 경제적 고충을 덜어주고자 정부는 2026년 6월 자산형성 정책금융의 완결판이라 불리는 청년미래적금을 전격 출범시켰습니다. 2025년 말을 끝으로 신규 모집을 마감한 기존 청년도약계좌는 만기가 5년(60개월)으로 너무 길어 이직이나 결혼, 독립 등 환경 변화가 잦은 청년들이 끝까지 유지하기 어려워 중도 해지율이 치솟는 구조적 한계를 안고 있었습니다.
청년미래적금은 현장의 이러한 목소리를 적극 수용하여 가입 기간을 현실적인 3년(36개월)으로 대폭 줄이고 월 납입 한도를 최대 50만 원 자유적립식으로 정비했습니다. 3년이라는 비교적 짧은 호흡 속에서 목돈 마련의 성취감을 직접 체감하고 경제적 자립을 조기에 달성할 수 있도록 정부가 정책적 사다리를 튼튼히 보강한 것입니다.
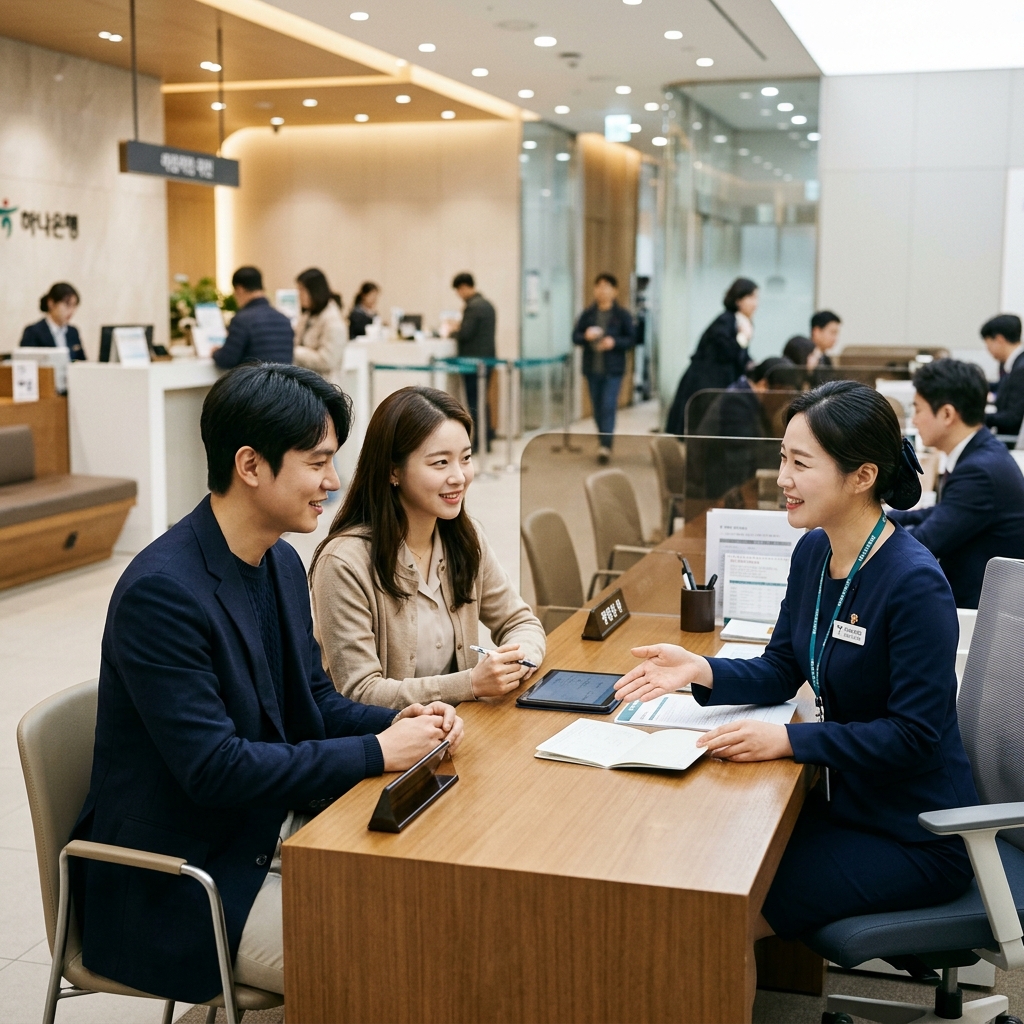
▲ 시중 은행 창구에서 청년 금융소비자가 청년미래적금의 최고 연 8.0% 금리 조건과 12% 정부기여금 매칭 혜택에 대해 전문 상담을 받고 있는 모습 / 청년 정책금융 현장 포커스
2. 연령과 소득 3대 핵심 축 및 청년미래적금 신혼부부 250% 특례 요건
청년미래적금의 문을 열기 위해서는 연령, 개인소득, 가구소득이라는 3대 자격 요건을 고루 충족해야 합니다. 대상 연령은 계좌 개설일 기준 만 19세부터 34세까지이며, 국방의 의무를 마친 청년은 군 복무 기간(최대 6년)을 현재 나이에서 깎아주어 최대 만 40세까지 넉넉하게 신청할 수 있습니다. 또한 청년도약계좌 종료와 새 제도 출범 사이의 공백기로 불이익을 본 1991년 1월부터 8월생 청년들에게도 특별 경과조치가 적용되어 만 35세가 되었더라도 가입 자격이 인정됩니다.
개인소득은 직전 과세기간인 2025년 국세청 확정 소득을 기준으로 엄격하게 따집니다. 2025년 총급여 7,500만 원 이하(종합소득 6,300만 원 이하)인 근로자와 사업소득자라면 누구나 가입할 수 있습니다. 다만 정부기여금을 매칭받기 위해서는 총급여가 6,000만 원 이하(종합소득 4,800만 원 이하, 소상공인 연매출 3억 원 이하)여야 하며, 총급여 6,000만 원 초과부터 7,500만 원 이하 구간은 정부기여금 없이 이자소득 비과세 혜택만 누릴 수 있습니다. 최근 3년 중 한 번이라도 금융소득이 2,000만 원을 넘어 종합과세 대상자가 된 적이 있다면 가입이 차단됩니다.
가구소득은 주민등록등본상 함께 사는 가족의 소득 합계가 기준 중위소득 200% 이하(일반형)이거나 150% 이하(우대형)여야 합니다. 1인 가구 기준 중위 200%는 연 약 6,154만 원, 2인 가구는 연 약 1억 78만 원, 3인 가구는 연 약 1억 2,862만 원 선입니다. 특히 결혼 후 맞벌이로 합산 소득이 늘어나 정부 지원에서 억울하게 탈락하는 신혼부부를 위해 2인 맞벌이 특례 기준을 신설했습니다. 부부로만 구성된 2인 가구는 일반형이 중위소득 250%(연 1억 2,597만 원)까지, 우대형은 200%(연 1억 78만 원)까지 대폭 완화되어 맞벌이 청년들의 진입 장벽을 획기적으로 낮췄습니다.
지원 유형 및 소득 요건
가구 중위소득 기준
정부기여금 매칭 비율
3년 만기 예상 수령액 (은행 8%)
우대형 (중기재직·소상공인)
총급여 3.6천만·매출 1억 이하 (중위 150%)
납입액 12% (3년 총 216만 원 지원)
총 2,255만 원 (실질수익률 연 19.4%)
일반형 (일반소득자)
총급여 6천만·매출 3억 이하 (중위 200%)
납입액 6% (3년 총 108만 원 지원)
총 2,138만 원 (실질수익률 연 14.4%)
세제혜택형 (소득초과)
총급여 6천만 초과 ~ 7.5천만 원 이하
정부기여금 미지급 (비과세 전액 유지)
총 2,039만 원 (이자소득세 15.4% 면제)
취급기관별 최고 금리
농협·우리·신한·국민·기업·하나·우체국
기본금리 5% + 은행우대 2~3%p
최고 연 8.0% 3년 고정금리 제공
도약계좌 갈아타기
기존 5년 만기 도약계좌 보유자 대상
특별중도해지로 기존 기여금·비과세 보전
11월 16~27일 미래적금 선개설 후 특별해지
SPONSORED · ADVERTISEMENT
3. 일반형 6% 대비 우대형 12% 정부기여금과 청년미래적금 연 19.4% 환산 수익률
청년미래적금의 가장 매력적인 혜택은 매월 본인이 저축한 금액에 정부가 정해진 비율대로 얹어주는 정부기여금입니다. 기존 도약계좌가 소득 구간별로 월 2만 1천 원부터 3만 3천 원까지 복잡하게 차등 지급했던 방식에서 탈피하여, 납입액 대비 명쾌한 고정 매칭 비율을 도입했습니다.
기본 지원인 일반형은 본인 납입액의 6%를 매칭하여 매월 최대 3만 원, 3년간 총 108만 원을 지원합니다. 반면 총급여 3,600만 원 이하이면서 중소기업에 재직 중인 청년 근로자에게 주어지는 우대형은 무려 12%를 매칭하여 매월 최대 6만 원, 3년간 총 216만 원이라는 파격적인 지원금을 얹어줍니다.
월 50만 원씩 3년간 성실히 채워 넣으면 본인 원금은 1,800만 원이 됩니다. 여기에 최고 연 8.0% 금리를 적용받는 우대형 가입자는 원금 1,800만 원에 정부기여금 216만 원, 은행 이자 230만 원과 기여금에서 발생한 기본 이자 8만 원이 더해져 만기에 약 2,255만 원의 목돈을 쥐게 됩니다. 발생한 모든 이자에 대해 15.4%의 이자소득세가 전액 비과세되므로, 이를 일반 시중은행의 과세 적금으로 환산하면 무려 세전 연 19.4%에 달하는 믿기 힘든 고수익률을 기록하게 됩니다. 일반형 역시 세전 연 14.4% 수준의 강력한 수익률을 안겨줍니다.
▲ 청년미래적금 가입자가 스마트폰 모바일 뱅킹 앱을 통해 자격 심사 결과와 매월 50만 원 분할 적립 현황 및 비과세 혜택을 실시간 확인하고 있는 모습 / 모바일 자산관리 현장 자료
4. 14개 은행별 우대금리 조건 비교와 청년미래적금 최고 연 8.0% 공략법
청년미래적금을 취급하는 14개 금융기관은 모두 가입 후 3년간 변함없는 연 5.00%의 기본금리를 보장합니다. 따라서 만기 수령액을 조금이라도 더 늘리려면 각 은행이 내건 우대금리(최대 2.0%p~3.0%p) 조건을 꼼꼼히 따져본 뒤 본인의 소비 생활에 가장 유리한 주거래 은행을 택해야 합니다. 1%포인트의 금리 차이는 3년 만기 시 약 27만 7,500원의 수령액 차이로 직결됩니다.
모든 은행에 똑같이 적용되는 공통 우대금리는 총 0.7%포인트입니다. 2025년 총급여 3,600만 원(종합소득 2,600만 원) 이하 청년에게 자동으로 붙는 소득 우대금리 0.5%포인트와, 금융위원회 서민금융진흥원의 무료 1:1 맞춤형 재무상담을 만기 3개월 전까지 이수하면 주어지는 0.2%포인트가 여기에 해당합니다.
시중 6대 은행(농협, 신한, 우리, 하나, 기업, 국민)과 우체국은 최고 연 8.00%를 제공하며, 지방은행들과 카카오뱅크는 최고 연 7.00%를 제공합니다. 농협은 급여 18개월 이체와 카드 월 20만 원 사용 시 최고 금리를 주며, 우리은행은 급여 18회 입금과 연계 결제 실적으로 우대를 채웁니다. 신한은행은 직전 6개월간 소득 이체가 없었던 신규 고객에게 1.0%포인트의 강력한 특별 우대를 얹어줍니다. 기업은행은 중소기업 재직자 0.3%포인트 추가 우대를 두고 있으며, 우체국은 계좌개설 이벤트로 1.0%포인트를 손쉽게 지원하므로 본인의 급여 통장 및 주 결제 카드와 일치하는 은행을 전략적으로 선택해야 합니다.
현재 청년도약계좌를 붓고 있는 수많은 청년들이 청년미래적금으로 갈아타야 할지 깊은 고민에 빠져 있습니다. 두 제도는 동일한 정책금융 상품이므로 원칙적으로 동시에 복수 계좌를 가질 수는 없습니다. 하지만 정부는 5년 유지가 버거운 청년들을 위해 특별중도해지 방식을 통한 공식 갈아타기를 활짝 열어두었습니다.
갈아타기를 결심했다면 절대로 실수해서는 안 되는 치명적인 행정 순서가 있습니다. 바로 선 개설 후 해지 원칙입니다. 청년미래적금 가입 자격 심사를 거쳐 승인을 받은 뒤, 은행 앱에서 반드시 청년미래적금 통장을 먼저 개설하고 난 다음에 비로소 기존 청년도약계좌의 특별중도해지를 신청해야 합니다. 만약 마음이 급해 도약계좌를 먼저 덜컥 해지해 버리면 일반 중도해지로 처리되어 그동안 모아둔 정부기여금이 전액 환수되고 비과세 혜택도 물거품이 됩니다. 또한 도약계좌를 해지하고 받은 목돈은 미래적금에 한꺼번에 넣을 수 없으며 본인 입출금 통장으로 입금된 뒤 미래적금에는 매월 50만 원씩 새롭게 부어야 합니다.
실익을 따져보면 5년 만기 완주에 대한 부담이 크거나 중소기업 우대형(12% 기여금)에 해당하는 청년은 갈아타는 것이 압도적으로 유리합니다. 예를 들어 2024년 6월 가입 후 29회차를 채운 청년이 갈아탈 경우 약 2,253만 원을 즉시 손에 쥐며, 향후 3년간 미래적금에 붓는 돈에 대해 연 11.2%의 높은 단리 효과를 누릴 수 있습니다. 반면 납입 여력이 충분해 월 70만 원을 꽉 채워 5년 만기에 5천만 원 수준의 거대 목돈을 쥐고 싶거나 가입 자격을 초과한 청년이라면 기존 계좌를 유지하는 것이 현명합니다.
Mastering the 2026 Youth Future Savings Account: A Comprehensive Overview of the Three Key Enrollment Criteria, 8% Interest Rate, and Benefits of Switching to the Leap Account.
The Youth Future Savings Account, launched in June 2026, is garnering explosive interest from the 2030 generation as it alleviates the burden of long-term contributions that have hindered asset formation among young people. This product significantly shortens the existing Youth Leap Account's five-year term to a more realistic three years and is designed for flexible savings of up to 500,000 KRW per month. It offers an extraordinary interest rate of up to 8.0% per annum, combined with a government contribution that can reach up to 12% of the individual's contributions, and a full tax exemption of 15.4%. This results in an astonishing pre-tax annual yield of 19.4% based on standard savings accounts. The eligibility criteria include individuals aged 19 to 34 (up to 40 years for those serving in the military), an income requirement of 75 million KRW or less in total salary for 2025, and a special provision for newlywed couples with a combined income of up to 250% of the median income. Additionally, we will summarize key issues for young financial consumers, including strategies for preferential interest rates from 14 different banks and the benefits of switching from existing Youth Leap Account holders to this new offering.
📌 Key Takeaways
14 banks guarantee a basic annual interest rate of 5.0% and provide a full exemption from the 15.4% interest income tax.
With a preferential monthly support of up to 60,000 won (totaling 2.16 million won over three years), the pre-tax equivalent annual interest rate for regular savings can reach 19.4%.
For newlywed couples, the household income limit has been relaxed to 250% (annual income of 125 million won), ensuring the preservation of contributions by adhering to the order of special withdrawals after account opening.
1. Background of the 3-Year Term Reduction and Launch of the Youth Future Savings Account Amidst Youth Debt Reality
The economic indicators facing young people taking their first steps into society are becoming increasingly harsh year by year. According to surveys on the living conditions of youth conducted by the National Statistical Office and relevant ministries, the average annual income of individuals aged 19 to 34 remains at approximately 26.25 million won, while the average debt has surged to 16.37 million won, nearly a 40% increase in just the past two years. Notably, over 70% of youth debt is tied to housing-related loans, leaving them vulnerable to the shocks of steep interest rate hikes and fluctuations in housing prices.
In response to the economic hardships faced by the youth, the government has launched the Youth Future Savings Account, touted as the ultimate asset formation policy financial tool, in June 2026. The existing Youth Leap Account, which will cease new enrollments by the end of 2025, has a five-year (60-month) maturity period that is too long for young people who frequently experience changes in their circumstances due to job transitions, marriage, or independence, resulting in a high rate of early withdrawals.
The Youth Future Savings Account has actively incorporated feedback from the field by significantly reducing the subscription period to a realistic three years (36 months) and establishing a maximum monthly contribution limit of 500,000 won in a flexible savings format. This shorter term allows young individuals to experience the satisfaction of accumulating a substantial amount of savings and achieve economic independence more quickly, with the government reinforcing the policy ladder to support them.
▲ A young financial consumer receiving consultation on the 8.0% interest rate and 12% government matching contribution of the Youth Future Savings at a bank counter / Youth Policy Finance Focus
2. Three Core Criteria of Age and Income, and Special Conditions for Newlyweds under the Youth Future Savings Account
To open a Youth Future Savings Account, applicants must meet three core eligibility criteria: age, individual income, and household income. The eligible age range is from 19 to 34 years old as of the account opening date, and young individuals who have completed their military service can subtract their service period (up to six years) from their current age, allowing them to apply until the age of 40. Additionally, special transitional measures apply to young individuals born between January and August 1991, who were disadvantaged during the gap between the closure of the Youth Leap Account and the launch of the new system, allowing them to qualify even if they are now 35 years old.
Individual income is strictly assessed based on the confirmed income from the National Tax Service for the previous tax year, 2025. Any worker or self-employed individual with a total salary of 75 million won or less (or comprehensive income of 63 million won or less) can apply. However, to receive matching government contributions, total salary must be 60 million won or less (comprehensive income of 48 million won or less, or annual revenue of 300 million won or less for small business owners). Those who have been subject to comprehensive taxation due to financial income exceeding 20 million won in any of the last three years are barred from applying.
Household income must be the sum of the incomes of family members living together, which should be at or below 200% of the median income (standard type) or 150% (preferred type). For a one-person household, the median income at 200% is approximately 61.54 million won annually, for a two-person household it is about 100.78 million won, and for a three-person household, it is around 128.62 million won annually. To address the issue of newlywed couples who may unfairly miss out on government support due to increased combined income from dual earners, a special provision for two-person dual-income households has been established. For couples, the standard type is relaxed to 250% of the median income (approximately 125.97 million won annually), while the preferred type is set at 200% (approximately 100.78 million won), significantly lowering the entry barrier for dual-income youth.
Category
Target Scope
Standard / Benefit
Procedure / Action
Preferred Type (Small Business Owners and Self-Employed)
Total salary of 36 million won; sales below 100 million won (median 150%)
Contribution rate of 12% (total support of 2.16 million won over 3 years)
Total of 22.55 million won (real yield rate of 19.4% per year)
General Type (Regular Income Earners)
Total salary of 60 million won; sales below 300 million won (median 200%)
Contribution rate of 6% (total support of 1.08 million won over 3 years)
Total of 21.38 million won (real yield rate of 14.4% per year)
Tax Benefit Type (Exceeding Income)
Total salary exceeding 60 million won and up to 75 million won
No government contribution (full tax exemption maintained)
Total of 20.39 million won (exemption from interest income tax of 15.4%)
Maximum Interest Rates by Financial Institutions
NongHyup, Woori, Shinhan, KB, KEB Hana, and Post Office
Base interest rate of 5% + bank preferential rate of 2-3 percentage points
Maximum fixed interest rate of 8.0% for 3 years
Switching Jump Accounts
Targeting existing holders of 5-year maturity jump accounts
Special early termination to preserve existing contributions and tax exemptions
Special termination available after pre-opening Future Savings from November 16 to 27.
3. Government Contribution Rates of 6% for Standard Type vs. 12% for Preferred Type, and an Impressive Annual Yield of 19.4% for the Youth Future Savings Account
The most attractive benefit of the Youth Future Savings Account is the government contribution, which adds a predetermined percentage to the amount saved each month. Departing from the previous complex tiered payment system of the Leap Account, which offered varying monthly contributions from 21,000 won to 33,000 won based on income brackets, a clear fixed matching rate has been introduced.
The basic support, known as the standard type, matches 6% of the individual's contributions, providing a maximum of 30,000 won per month, totaling 1.08 million won over three years. In contrast, the preferred type, available to young workers earning a total salary of 36 million won or less and employed by small businesses, offers a remarkable 12% match, providing up to 60,000 won per month, amounting to a total of 2.16 million won over three years.
If a participant consistently contributes 500,000 won monthly for three years, their principal will amount to 18 million won. For those enrolled in the preferred type with a maximum annual interest rate of 8.0%, the total at maturity will include the principal of 18 million won, the government contribution of 2.16 million won, bank interest of 2.3 million won, and basic interest from the contribution of 80,000 won, resulting in approximately 22.55 million won at maturity. All interest earned is exempt from the 15.4% interest income tax, translating to an astonishing pre-tax annual yield of 19.4% when compared to taxable savings accounts at regular banks. The standard type also offers a strong pre-tax annual yield of around 14.4%.
▲ A subscriber reviewing their qualification status, monthly 500,000 KRW deposit schedule, and tax-exempt asset accumulation in real time via a mobile banking platform / Mobile Asset Management Reference
4. Comparison of Preferential Interest Rate Conditions Across 14 Banks and Strategies to Achieve the Maximum Annual Rate of 8.0% for the Youth Future Savings Account
The 14 financial institutions offering the Youth Future Savings Account guarantee a basic interest rate of 5.00% for the entire three-year period after enrollment. To maximize the maturity amount, individuals should carefully evaluate the preferential interest rate conditions (ranging from 2.0% to 3.0% points) offered by each bank and choose the one that best aligns with their spending habits. A one-percentage-point difference in interest rates can result in a difference of approximately 277,500 won at maturity.
A common preferential interest rate of 0.7% points applies to all banks. This includes a 0.5% point income preferential rate automatically granted to young individuals with a total salary of 36 million won or less (or comprehensive income of 26 million won or less), and an additional 0.2% point awarded for completing a free one-on-one personalized financial consultation from the Financial Services Commission's Financial Consumer Agency before three months to maturity.
The six major banks (NongHyup, Shinhan, Woori, Hana, KB Kookmin, and Industrial Bank) and the post office offer a maximum annual rate of 8.00%, while regional banks and Kakao Bank provide a maximum of 7.00%. NongHyup offers the highest rate for those who transfer their salary for 18 months and use a card for 200,000 won monthly, while Woori Bank provides preferential rates based on 18 salary deposits and linked payment performance. Shinhan Bank offers a strong special preference of 1.0% points for new customers who have not transferred income in the previous six months. Industrial Bank provides an additional 0.3% point preference for employees of small businesses, and the post office easily supports a 1.0% point preference through an account opening event, making it strategic to choose a bank that aligns with one’s salary account and primary payment card.
Many young individuals currently contributing to the Youth Leap Account are deeply contemplating whether to switch to the Youth Future Savings Account. Since both programs are identical policy financial products, it is generally not possible to hold multiple accounts simultaneously. However, the government has opened the door for a formal switch through a special early withdrawal method for those struggling with the five-year maintenance requirement.
If one decides to switch, there is a critical administrative sequence that must not be overlooked: the principle of opening a new account before closing the old one. After passing the eligibility review for the Youth Future Savings Account, individuals must first open the new account through their bank app and only then apply for the special early withdrawal of the existing Youth Leap Account. If one hastily closes the Leap Account first, it will be treated as a regular early withdrawal, resulting in the total forfeiture of accumulated government contributions and the loss of tax exemption benefits. Additionally, any funds received from closing the Leap Account cannot be deposited directly into the Future Savings Account; they must first be deposited into a personal checking account and then contributed monthly at 500,000 won into the Future Savings Account.
In terms of practicality, it is overwhelmingly advantageous for those burdened by the five-year maturity requirement or qualifying for the small business preferred type (with a 12% contribution) to switch. For example, a young individual who joins in June 2024 and completes 29 contributions would receive approximately 22.53 million won immediately upon switching and enjoy a high simple interest effect of 11.2% on the funds contributed to the Future Savings Account over the next three years. Conversely, for those with sufficient contribution capacity who wish to maximize their savings to around 50 million won at maturity by contributing 700,000 won monthly for five years, or for those who exceed the eligibility criteria, maintaining the existing account would be the wiser choice.
Recommended Deep-Dive Investigations TOP 3
GLOBAL REPORT
1월이 시작되면 감기는 이미 우리 곁에 와 있습니다. 2월, 3월, 4월까지 이어지는 추위와 건조함은 코와 목을 가장 먼저 공격합니다. 아침에 일어나자마자 막혀 있는 코. 계속 흐르는 콧물. 괜히 칼칼해지는 목. 이 증상은 “시작”일 뿐입니다. 한 번 무너지면 일주일, 길면 한 달까지 끌고 갑니다. 약을 먹으면 잠깐 괜찮아집니다. 하지만 며칠 뒤 또 반복됩니다. 왜일까요? 감기는 ‘치료’의 문제가 아니라 ‘관리’의 문제이기 때문입니다. 대부분은 감기가 오고 나서 약을 찾습니다. 하지만 진짜 중요한 건 감기가 오기 전에 코와 목을 지키는 것입니다. 건조한 실내 공기, 차가운 바깥 공기, 눈에 보이지 않는 세균. 코와 목은 매일 공격받고 있습니다. 지긋지긋하죠! 그런데도 우리는 아무 준비 없이 버티고 있습니다. 이번 겨울도 그렇게 보낼 건가요? 사실 방법은 어렵지 않습니다. 코를 깨끗하게 관리하고, 목을 따뜻하게 보호하고, 점막을 촉촉하게 유지하고, 기관지를 미리 관리하고, 외부 공기를 차단하는 것. 이 다섯 가지만 꾸준히 해도 감기약 없이 겨울을 보내는 것이 충분히 가능합니다. 🔥 이제부터 그 방법을 하나씩 살펴보겠습니다. 🔥 1. 코와 목을 먼저 관리해야 하는 과학적 이유 감기의 대부분은 코 점막에서 시작됩니다. 국제 학술지 Nature Reviews Microbiology 와 Journal of Allergy and Clinical Immunology 에 실린 호흡기 감염 관련 연구들에서는, 감기 바이러스가 비강 상피세포에 먼저 부착해 증식한다는 점을 설명하고 ...
리모델링사업이 진행 중인 아파트를 매매할 때 “계약금 10%를 언제까지 내야 하느냐”는 질문이 특히 많이 나옵니다. 이주공고(이주 안내)가 7~11월쯤이라고 들으면, 그 시점에 맞춰 계약금도 움직일 것 같아서 더 헷갈리기 쉽습니다. 하지만 실제 납부기한은 ‘이주공고가 언제냐’만으로 자동 결정되지 않는 경우가 많습니다. 1) 계약금 10% 납부기한: 결국 ‘문서에 적힌 일정’이 기준 계약금 10%를 언제까지 납부해야 하는지는, 내가 서명하는 매매계약서(특약 포함) 와 사업주체/조합이 제시한 공고·안내문 에 적힌 납부 일정이 기준이 됩니다. 실제 공고문에서는 분양대금 납부의 큰 틀(계약금→중도금→잔금)을 먼저 안내하고, 상세 일정은 별도 표나 유의사항으로 제시하는 방식이 흔합니다. 또, 계약서 문구에 따라 지급 시점이 조건부로 설정될 수도 있습니다. 예를 들어 한 사례 소개 자료에서는 용역계약서에 잔금(10%) 지급시기가 “사업승인 후”로 기재되어 있었다는 점이 언급됩니다. 이런 식으로 ‘사업 단계’와 지급을 연동하는 문구가 들어가면, 질문의 답은 계약서 문구를 확인해야만 확정됩니다. 관련 내용은 링크 에서 문구 사례를 확인할 수 있습니다. 2) 입주자모집공고에서 확인되는 ‘납부 순서’와 잔금 마감 시점 공고문에 적힌 문구를 보면, 납부 순서와 잔금 마감에 대한 기준이 비교적 명확하게 제시되는 경우가 있습니다. 예를 들어 한 입주자모집공고에는 “분양금액(주택가격)은 계약금, 중도금, 잔금의 순서로 납부”하며 “잔금은 입주(열쇠 수령일) 전에 완납”해야 한다고 안내되어 있습니다. (문구 확인: 링크 ) 이 문구가 의미하는 바는 최소 2가지입니다. 분양/공급 형태의 문서에서는 ‘계약금→중도금→잔금’ 흐름이 공식적으로 안내될 수 있습니다. 잔금은 “입주(열쇠 수령)” 이전에 완납해야 한다는 마감 기준이 문서에 적혀 있을 수 있습니다. 다만, 위 공고문 문구는 잔금 마감에 대한 기준을 보여주지만, 계약금 10%의...
윤석열 전 대통령 탄핵 인용 소식을 접하면, 가장 궁금한 지점은 ‘헌재가 정확히 무엇을 위헌·위법으로 봤는가’입니다. 또한 탄핵과 별개로 진행되는 형사재판(내란 우두머리 혐의 등)이 어디까지 왔는지도 함께 정리할 필요가 있습니다. 아래 내용은 제공된 기사/게시물 스니펫과 링크에서 확인되는 범위만 모아, 일반인이 흐름을 이해하기 쉽게 정리한 것입니다. 1) 탄핵 인용 관련: 스니펫에서 확인되는 ‘판단의 골격’ 제공된 근거 중 조국혁신당 사이트에는 헌법재판소가 윤석열 탄핵 심판에서 “피청구인의 위헌·위법행위는 국민 신임 …”이라는 취지로 판단했다는 문장이 인용돼 있습니다( 링크 ). 이 인용문만 놓고 보면, ‘위헌·위법행위’가 있었는지와 그로 인해 ‘국민의 신임’이 어떻게 평가됐는지가 핵심 축으로 소개됩니다. 다만 질문에서 요청하신 세부 항목, 즉 비상계엄 선포 자체를 문제 삼은 구체적 이유, 계엄 이후 조치(포고령, 국회 통제 등)의 어떤 지점이 헌법 위반인지, 국회의 권한행사 방해 및 정치활동 제약을 어떤 논리로 판단했는지 등은, 이번에 제공된 근거의 제목/스니펫만으로는 조항·사실관계·판단 구조가 그대로 제시돼 있지 않습니다. 따라서 이 글에서는 ‘헌재가 무엇을 문제 삼았다’는 세부 리스트를 단정적으로 재구성하기보다, 현재 확인 가능한 문구 수준의 요약(위헌·위법행위 → 국민 신임의 문제로 평가)까지만 적습니다. 만약 헌재 결정문 전문(주문 및 이유)이 추가로 확인되면, 그때는 문장 단위로 ‘어떤 행위’와 ‘어떤 헌법 원리/조항’이 연결되는지(예: 권력분립, 국회의 권한, 정치적 기본권 등) 구조화해 정리하는 것이 가장 정확합니다. 2) 형사 절차(내란 혐의) 관련: 체포영장과 1심 선고 언급 탄핵 심판과 별도로, 12·3 비상계엄 사태로 내란 혐의를 받는 윤석열 대통령에 대해 2024년 12월 31일 체포 영장이 발부됐다는 BBC 보도가 있습니다( 링크 ). 해당 보도는 ‘현직 대통령’에 대한 체포영장 발부라는 점을 함께 언급합니다. 또...