▲ 16년 만에 사명을 변경하고 새롭게 출범한 트리니티항공 여객기 및 브랜드 / 공식 배포 사진
대한민국 저비용항공사(LCC) 업계의 핵심 축이었던 티웨이항공이 16년 만에 사명을 '트리니티항공(Trinity Airways)'으로 전격 교체하며 항공업계와 자본시장의 뜨거운 감자로 부상했습니다. 단순히 브랜드 로고와 유니폼을 바꾸는 표면적 리브랜딩을 넘어, 저가 항공의 틀을 깨고 대형항공사(FSC)와의 경계를 허무는 '선택적 서비스 항공사(SSC)' 모델을 제시하고 인천공항 제1여객터미널(T1)의 프리미엄 인프라를 대거 선점하고 나섰기 때문입니다. 특히 대명소노그룹과의 결합을 통해 항공과 호텔·리조트를 잇는 종합 레저 플랫폼으로의 대전환을 꾀하고 있으나, 2,000%에 달하는 높은 부채비율과 600억 원대의 외화환산손실 등 금융비용 부담은 향후 장기 연착륙을 가를 중대한 시험대로 지목되고 있습니다.
핵심 팩트 브리핑
팩트 검증 지표 1: 16년 만의 사명 교체 및 SSC 전략 도입: 2026년 9월 10일 '트리니티항공' 공식 출범(코드 TW 유지), 단거리 실속 운임부터 중·장거리 무료 기내식 및 프리미엄 비즈니스 풀코스(장어덮밥·트러플파스타) 차등화
팩트 검증 지표 2: 인천공항 T1 프리미엄 인프라 선점 및 노선 확장: 옛 아시아나 A카운터 및 동편 라운지 임차 추진, 차세대 A330-900neo 도입 및 12월 18일 인천~고베 매일 신규 취항, 안전 투자 1조 6,290억 원 책정
팩트 검증 지표 3: 재무적 양면성: 1분기 매출 6,121억 원(+37%) 및 영업이익 192억 원 흑자 달성했으나, 고유가·환율에 따른 금융비용(605억 원)으로 순손실 -167억 원 및 부채비율 1,947%~2,311% 상존
SPONSORED · ADVERTISEMENT
1. 16년 만의 파격 리브랜딩: '티웨이' 버리고 '삼위일체' 트리니티로
항공업계와 금융감독원 전자공시에 따르면, 티웨이항공은 2026년 9월 10일을 기점으로 사명을 '트리니티항공(Trinity Airways)'으로 전격 변경하고 국내선과 국제선에 새 브랜드를 일제히 적용했습니다. 이는 2004년 국내 최초 저비용항공사인 한성항공으로 출범해 2010년 티웨이항공으로 재출범한 지 16년 만이자, 제주항공에 이어 국내 LCC 2위 자리를 굳혀온 핵심 브랜드의 역사적 전환점입니다.
새 사명 '트리니티(TRINITY)'는 라틴어 '삼위일체(Trinitas)'에서 유래한 것으로, '셋이 하나로 모여 완전함을 이룬다'는 철학적 가치를 내포하고 있습니다. 이는 단순한 여객 운송에 안주하지 않고, 모기업인 대명소노그룹(소노인터내셔널)의 강력한 호스피탈리티(호텔·리조트) 및 레저 인프라를 유기적으로 결합하여 완성형 여행 플랫폼으로 도약하겠다는 포부를 담고 있습니다.
트리니티항공은 사명 변경 첫날 김포~제주 노선에 신규 CI 리버리가 적용된 B737-8 항공기를 전격 투입했습니다. 승객 혼선을 방지하기 위해 국제항공운송협회(IATA) 2레터 식별 코드인 'TW'와 기존 편명, 예약 발권 시스템 및 공항 체크인 카운터 위치는 그대로 유지하면서, 기체 도장, 객실 승무원 유니폼, 모바일 앱 환경을 고급스럽게 전면 개편했습니다.
2. LCC와 FSC의 경계를 허물다: 'SSC(선택적 서비스)' 전략의 승부수
트리니티항공이 업계의 비상한 관심을 끄는 가장 본질적인 배경은 기존 저비용항공사(LCC)와 대형항공사(FSC)의 이분법적 틀을 허무는 'SSC(Selective Service Carrier, 선택적 서비스 항공사)' 모델을 천명했기 때문입니다. 이상윤 트리니티항공 사장은 'SSC는 단순한 분류가 아닌 핵심 사업 방향으로, 고객이 진정 가치를 느끼는 영역에는 과감히 투자하고 비효율적인 거품은 걷어내겠다'고 강조했습니다.
트리니티항공의 SSC 전략은 노선별 승객 수요에 맞춰 정밀하게 차별화됩니다. 단거리 노선(일본·대만 등)에서는 기존 LCC 고유의 실속 있는 운임 경쟁력을 극대화하는 반면, 중거리 노선(자카르타·싱가포르 등)에서는 전 승객 무료 음료와 1회의 무료 기내식을 기본 제공합니다. 나아가 유럽·시드니·밴쿠버 등 장거리 노선에서는 2회의 무료 기내식과 전용 체크인, 프리미엄 라운지 혜택을 패키지로 연계합니다.
특히 비즈니스 클래스 기내식은 민물장어덮밥, 트러플 크림 치킨 파스타 등 고급 메인 요리에 신선한 샐러드, 제철 과일, 식전빵, 요거트, 프리미엄 와인과 맥주를 곁들인 풀코스 한 상 차림으로 대폭 업그레이드되었습니다. 합리적인 가격에 대형사 못지않은 고품격 서비스를 누릴 수 있다는 입소문이 퍼지며 상용 승객들의 재탑승률이 가파르게 상승하고 있습니다.
▲ 인천국제공항 활주로에서 힘차게 이륙 중인 트리니티항공 최신예 차세대 여객기 / 공식 항공 프레스 사진
3. 인천공항 T1 지각변동: 아시아나 빈자리 메우는 프리미엄 인프라
대한항공과 아시아나항공의 합병에 따른 인천국제공항 터미널 재편은 트리니티항공에 유례없는 인프라 도약의 기회를 제공했습니다. 트리니티항공은 아시아나항공이 비운 인천공항 제1여객터미널(T1) 동편 출국장 바로 앞 프리미엄 체크인 'A카운터'를 확보하여 비즈니스 승객과 상위 등급 회원에게 초고속 탑승수속을 제공하기 시작했습니다.
또한 T1 동편에 위치했던 옛 아시아나항공 전용 라운지 2개 공간에 대한 임차 의향서를 인천국제공항공사에 공식 제출하고 단독 라운지 개설 협의를 진행 중입니다. 라운지가 완공되면 LCC 태생 항공사로서는 국내 최초로 인천공항 핵심 구역에 독립 프리미엄 라운지를 운영하게 됩니다.
기재 현대화와 네트워크 확장도 급물살을 타고 있습니다. 현재 운용 중인 47대의 기단에 더해, 연료 효율이 25% 개선된 차세대 중대형기 에어버스 A330-900neo와 보잉 B737-8을 연내 순차 인도받습니다. 오는 2026년 12월 18일부터는 인천~고베 노선에 매일 왕복 1회(인천 14:10 출발 ➔ 고베 15:55 도착 / 고베 16:55 출발 ➔ 인천 18:55 도착) 신규 취항하며, 부다페스트 등 동유럽 및 미주 노선 취항을 본격화합니다. 아울러 연간 항공안전 투자액으로 LCC 최대인 1조 6,290억 원을 편성해 운항 신뢰성을 확고히 다지고 있습니다.
4. 소노트리니티그룹과의 결합: 항공과 리조트 잇는 '통합 레저 플랫폼'
트리니티항공의 가장 독보적인 경쟁 무기는 모기업인 대명소노그룹(소노인터내셔널)의 막강한 호스피탈리티 자산과의 유기적 결합입니다. 국내외 굴지의 리조트 및 호텔 체인을 거느린 소노그룹에 편입된 이후, 항공 운송권과 숙박 인프라를 단일 번들로 묶어내는 사업 시너지가 본격화되고 있습니다.
첫째, 항공 마일리지와 소노 호텔·리조트 멤버십 포인트를 1:1 교차 적립 및 사용할 수 있는 통합 로열티 체계가 구축되고 있습니다. 둘째, 아시아 및 유럽 등 주요 취항지 노선과 현지 소노 리조트를 연계한 독점 에어텔(Air-Tel) 결합 패키지 상품을 잇달아 출시하며 유통 중간 마진을 획기적으로 낮췄습니다.
이러한 결합 구조는 수백만 명에 달하는 기존 소노그룹 충성 회원층을 자연스럽게 트리니티항공의 탑승객으로 유입시키고, 항공 승객을 다시 리조트 객실과 레저 시설로 재순환시키는 강력한 선순환 수요 파이프라인을 창출하고 있습니다. 이는 단순한 가격 출혈 경쟁에 매몰되었던 기존 LCC의 한계를 넘어 고부가가치 종합 여행 플랫폼 기업으로 거듭나는 결정적 발판이 되고 있습니다.
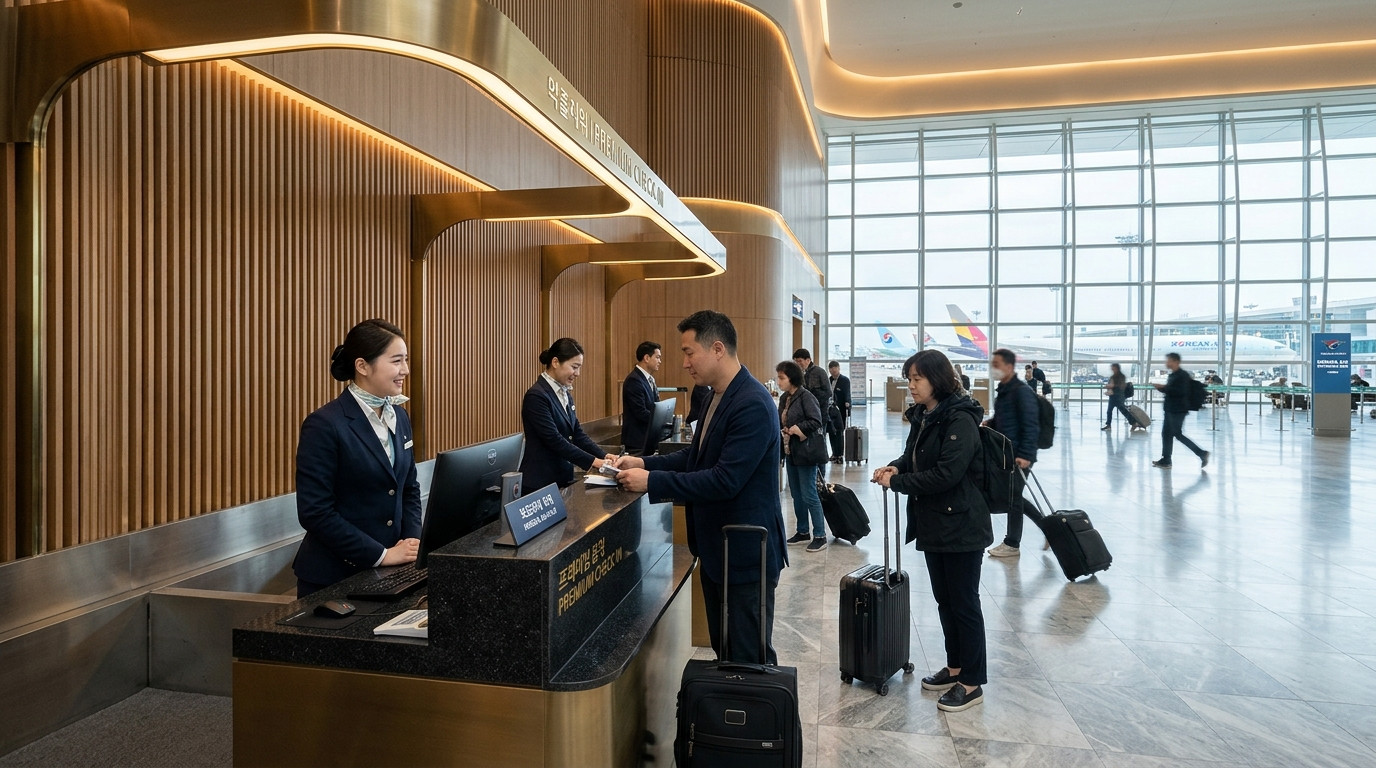
▲ 인천국제공항 제1여객터미널(T1) 프리미엄 체크인 카운터 및 비즈니스 라운지 전경 / 공항 인프라 보도자료사진
5. 외형 성장에 감춰진 '재무적 그림자': 영업흑자에도 순손실 지속되는 까닭
트리니티항공의 눈부신 외형 확장과 공격적인 마케팅 이면에는 자본시장이 가장 면밀히 주시하는 '재무적 뇌관'이 자리 잡고 있습니다. 금융감독원 공시 자료에 따르면, 2026년 1분기 트리니티항공은 전년 동기 대비 37% 급증한 6,121억 원의 매출과 192억 원의 영업이익을 달성하며 분기 흑자 전환에 성공했습니다.
그러나 당기순손익을 들여다보면 167억 원의 순손실을 기록하며 적자의 늪을 벗어나지 못했습니다. 영업이익(192억 원)의 3배가 넘는 605억 원의 금융비용이 발생했기 때문입니다. 국제유가가 배럴당 100달러를 돌파하고 아시아 항공유(Jet Fuel) 가격이 157.89달러까지 폭등한 데다, 원/달러 환율이 1,400원 후반대에서 고착화되면서 항공기 리스료에 대한 막대한 외화환산손실과 이자 비용이 실적을 갉아먹었습니다.
가장 심각한 지표는 1,947%에서 최대 2,311%에 달하는 기형적인 부채비율입니다. 유상증자를 통해 자본 잠식을 해소하고 현금성 자산을 3,095억 원까지 확충했으며, 영업활동 현금흐름도 1,493억 원으로 개선되었으나 약 4,200억 원에 달하는 누적 미처리 결손금은 여전히 무거운 족쇄입니다. 결국 모기업의 자본 수혈에만 기댈 것이 아니라, A330-900neo 등 신규 도입 기재를 조기에 안정화시켜 실질적인 자체 잉여현금흐름(FCF)을 창출할 수 있느냐가 트리니티항공의 명운을 좌우할 핵심 잣대가 될 것입니다.
▲ Newly Rebranded Trinity Airways Commercial Aircraft Operating at Incheon International Airport / Official Press Archive
Marking an aggressive break with 16 years of corporate heritage, South Korea's second-largest low-cost carrier, T'way Air, has officially rebranded as 'Trinity Airways,' triggering an intense industry-wide debate over the future of aviation business models. Transcending cosmetic alterations to corporate identity and flight attendant uniforms, the airline is introducing a disruptive 'Selective Service Carrier (SSC)' paradigm that dismantles the traditional dichotomy between budget carriers and legacy full-service airlines. Backed by parent company Daemyung Sono Group, Trinity Airways is aggressively capturing prime terminal infrastructure at Incheon Airport Terminal 1 to create an integrated air-and-hospitality travel ecosystem. However, a precarious debt ratio approaching 2,000% and acute foreign translation losses exceeding 60 billion won remain critical structural hurdles to its long-term viability.
Core Fact Briefing
Verified Metric 1: Historic 16-Year Rebranding & SSC Paradigm: Officially launched as 'Trinity Airways' on Sept 10, 2026 (retaining TW code), deploying a Selective Service Carrier model offering budget short-haul fares alongside complimentary multi-course dining on medium and long-haul routes.
Verified Metric 2: Capturing Incheon T1 Infrastructure & Network Growth: Securing Terminal 1's prime Check-in Counter A and former Asiana lounges, expanding fleet with fuel-efficient A330-900neos, launching daily Incheon-Kobe service on Dec 18, and allocating 1.63 trillion KRW for safety.
Verified Metric 3: Financial Dual Realities: Achieved record Q1 revenue of 612.1 billion KRW (+37%) and operating profit of 19.2 billion KRW, yet recorded a net loss of -16.7 billion KRW driven by 60.5 billion KRW in financial/FX expenses alongside a debt ratio near 2,000%.
1. A Historic 16-Year Pivot: Shedding T'way for 'Trinitas'
According to disclosures from regulatory filings and commercial aviation announcements, T'way Air officially changed its corporate identity to 'Trinity Airways' on September 10, 2026, deploying the new brand simultaneously across domestic and international operations. This marks the culmination of a 16-year operational era that began with Hansung Airlines in 2004 before rebranding to T'way Air in 2010, cementing its position as South Korea's second-largest low-cost carrier.
The corporate moniker 'Trinity' is derived from the Latin 'Trinitas' (Three in One), symbolizing structural completeness. Strategic planners emphasize that the rebranding represents far more than an aesthetic update; it reflects a long-term initiative to integrate airline transportation with the domestic and overseas hotel, resort, and leisure assets of parent company Daemyung Sono Group (Sono International).
On the inaugural day of operations, Trinity Airways deployed a newly painted Boeing 737-8 aircraft on the high-density Gimpo–Jeju route. To ensure continuity and prevent passenger disruption, the carrier retained its two-letter IATA identifier 'TW,' flight numbering schemes, and core ticketing platforms, while systematically overhauling aircraft liveries, cabin crew uniforms, airport signage, and mobile interfaces.
2. Redefining Market Segments: The 'Selective Service Carrier (SSC)' Gamble
The most structurally innovative dimension of Trinity Airways is its introduction of the 'Selective Service Carrier (SSC)' concept, deliberately breaking down the rigid boundary between low-cost and legacy full-service operations. As President Lee Sang-yoon affirmed during the brand unveiling, SSC is not merely a marketing label but the central operational strategy: aggressively investing in high-touch amenities that passengers genuinely value while eliminating structural cost inefficiencies.
Operationally, the SSC framework is tailored to stage length. Short-haul regional flights (Japan and Taiwan) prioritize unbundled low-fare efficiency. Conversely, medium-haul sectors (Jakarta and Singapore) now include complimentary bottled water, beverages, and a full in-flight meal. Long-haul routes (Europe, Sydney, and Vancouver) provide two complimentary full hot meal services alongside dedicated airport lounge access.
The carrier's business-class dining has undergone a particularly dramatic overhaul, featuring high-end Korean and Western entrées such as freshwater grilled eel over seasoned rice and truffle cream chicken pasta, served alongside fresh salads, seasonal fruits, artisan bread, and curated wine pairings. By delivering premium legacy comforts at an accessible price point, the carrier is capturing corporate travel demand traditionally reserved for full-service rivals.
▲ Trinity Airways Next-Generation Commercial Jet Taking Off from Incheon International Airport / Official Aviation Press Photo
3. Reshuffling Incheon Terminal 1: Capturing Premium Operational Space
The systemic consolidation between Korean Air and Asiana Airlines has triggered sweeping terminal realignments across Incheon International Airport, presenting Trinity Airways with prime commercial real estate. Capitalizing on operational shifts, Trinity secured Premium Check-in Counter A—situated directly adjacent to Terminal 1's East Departure Hall—providing frictionless express processing for premium travelers.
Simultaneously, the airline submitted formal letters of intent to the Incheon International Airport Corporation (IIAC) to lease two dedicated airport lounge spaces previously operated by Asiana Airlines in the east concourse of Terminal 1. Upon completion, Trinity will become the first carrier of low-cost heritage in Korea to maintain branded private passenger lounges within Incheon's premier terminal.
Fleet expansion and route diversification are advancing concurrently. Adding to its operational inventory of 47 aircraft, Trinity is taking delivery of modern, fuel-efficient Airbus A330-900neo widebodies alongside Boeing 737-8 narrowbodies. Beginning December 18, 2026, the carrier launches daily scheduled service on the Incheon–Kobe route (departing ICN at 14:10, arriving UKB at 15:55; returning UKB at 16:55, arriving ICN at 18:55), while accelerating expansion toward Budapest and North American markets backed by an industry-leading 1.63 trillion KRW safety expenditure budget.
4. Daemyung Sono Integration: Engineering a Unified Hospitality Platform
Trinity Airways' most formidable competitive differentiator lies in its deep operational synergy with its controlling shareholder, Daemyung Sono Group (Sono International). Possessing an extensive domestic and expanding international portfolio of luxury resorts and hotels, the group is integrating air travel and lodging into a singular, cohesive lifestyle ecosystem.
Core cross-platform initiatives include an integrated loyalty architecture that unifies airline frequent flyer miles with Sono resort membership rewards, allowing seamless reciprocal redemption. Furthermore, Trinity has launched exclusive bundled vacation packages pairing international flight segments directly with stays at Sono-operated overseas properties, capturing end-to-end travel expenditure without third-party intermediary leakage.
This commercial integration creates a self-reinforcing passenger pipeline: millions of domestic timeshare and resort club members are directed toward Trinity flights, while outbound international passengers are funneled into Sono's global hospitality properties. By establishing this cross-sectoral flywheel, the airline transcends traditional budget airline price wars, evolving into a diversified, high-margin leisure platform.
▲ Incheon International Airport Terminal 1 Premium Passenger Counter and Business Lounge Suite / Airport Press Archive
5. The Financial Shadow: Understanding High Debt Ratios and Currency Disparities
Beneath Trinity Airways' aggressive network expansion lies a precarious financial architecture that continues to draw acute scrutiny from institutional credit analysts. Regulatory filings indicate that during the first quarter of 2026, the airline achieved an impressive 37% year-over-year revenue surge to 612.1 billion KRW, successfully reversing an operating deficit to post an operating profit of 19.2 billion KRW.
Nevertheless, the bottom line tells a sobering story: Trinity logged a net quarterly loss of 16.7 billion KRW. This net deficit was precipitated by crushing financial expenses of 60.5 billion KRW—more than triple its operating earnings. With global crude benchmarks surpassing $100 per barrel and Asian aviation jet fuel climbing to $157.89, an entrenched high dollar exchange rate generated severe foreign exchange translation losses and escalating aircraft lease debt service.
The central balance-sheet vulnerability remains a debt ratio ranging between 1,947% and 2,311.66%. While recent equity rights offerings successfully erased capital impairment and built liquid reserves of 309.5 billion KRW, accumulated retained deficits of roughly 420 billion KRW constrain long-term capital allocation. Securing self-sustaining operational free cash flows through efficient widebody deployment will ultimately determine whether Trinity achieves enduring financial altitude.
Strategic Indicator
Q1 2026 Disclosed Financials
Operational Context & Core Highlights
Key Market Risks & Headwinds
Revenue & Operating Profit
Revenue 612.1B KRW / Op Profit 19.2B KRW
+37% YoY revenue growth; turnaround to operating black
Cumulative H1 operating deficit of 162.8B KRW reflects volatility
Net Loss & Financial Costs
Net Loss -16.7B KRW / Fin Costs 60.5B KRW
Financial overhead exceeded operating income by 3.1x
High FX rates escalate foreign currency aircraft lease charges
Debt Ratio & Deficits
Debt Ratio 1,947% to 2,311%
Capital impairment resolved (Total Equity: 90.5B KRW)
Retained deficit of 420B KRW strains solvency profile
Liquidity & Operating Cash
Cash 309.5B KRW / Op Cash Flow 149.3B KRW
Operating cash generation expanded 370% YoY
Managing CapEx for incoming A330-900neo deliveries
Incheon T1 & Route Network
Premium Counter A / 2 Private Lounges
Daily Incheon–Kobe service commences Dec 18, 2026
Establishing first independent lounge for budget heritage carrier
Special Reporting BureauPublisher & Editor-in-Chief: Dr. Seung Youb Ssin
MANINTOP NEWSLETTER
📬 만인의 탑 뉴스레터 무료 구독
오늘 보신 정책·시사 뉴스가 유익하셨나요? 매일 엄선되는 알짜 복지 혜택과 국회 실시간 속보를 이메일로 가장 먼저 받아보세요. (평생 무료)
Computer Programmer who love programming.
Computer Programmer Who love Riding Bicycle.
Computer Programmer who love trip in abroad.
Computer Programmer who love studying about programming
- even if sometimes it's very boring.
Computer Programmer who love talking with person.
- I love communication with person.
1월이 시작되면 감기는 이미 우리 곁에 와 있습니다. 2월, 3월, 4월까지 이어지는 추위와 건조함은 코와 목을 가장 먼저 공격합니다. 아침에 일어나자마자 막혀 있는 코. 계속 흐르는 콧물. 괜히 칼칼해지는 목. 이 증상은 “시작”일 뿐입니다. 한 번 무너지면 일주일, 길면 한 달까지 끌고 갑니다. 약을 먹으면 잠깐 괜찮아집니다. 하지만 며칠 뒤 또 반복됩니다. 왜일까요? 감기는 ‘치료’의 문제가 아니라 ‘관리’의 문제이기 때문입니다. 대부분은 감기가 오고 나서 약을 찾습니다. 하지만 진짜 중요한 건 감기가 오기 전에 코와 목을 지키는 것입니다. 건조한 실내 공기, 차가운 바깥 공기, 눈에 보이지 않는 세균. 코와 목은 매일 공격받고 있습니다. 지긋지긋하죠! 그런데도 우리는 아무 준비 없이 버티고 있습니다. 이번 겨울도 그렇게 보낼 건가요? 사실 방법은 어렵지 않습니다. 코를 깨끗하게 관리하고, 목을 따뜻하게 보호하고, 점막을 촉촉하게 유지하고, 기관지를 미리 관리하고, 외부 공기를 차단하는 것. 이 다섯 가지만 꾸준히 해도 감기약 없이 겨울을 보내는 것이 충분히 가능합니다. 🔥 이제부터 그 방법을 하나씩 살펴보겠습니다. 🔥 1. 코와 목을 먼저 관리해야 하는 과학적 이유 감기의 대부분은 코 점막에서 시작됩니다. 국제 학술지 Nature Reviews Microbiology 와 Journal of Allergy and Clinical Immunology 에 실린 호흡기 감염 관련 연구들에서는, 감기 바이러스가 비강 상피세포에 먼저 부착해 증식한다는 점을 설명하고 ...
리모델링사업이 진행 중인 아파트를 매매할 때 “계약금 10%를 언제까지 내야 하느냐”는 질문이 특히 많이 나옵니다. 이주공고(이주 안내)가 7~11월쯤이라고 들으면, 그 시점에 맞춰 계약금도 움직일 것 같아서 더 헷갈리기 쉽습니다. 하지만 실제 납부기한은 ‘이주공고가 언제냐’만으로 자동 결정되지 않는 경우가 많습니다. 1) 계약금 10% 납부기한: 결국 ‘문서에 적힌 일정’이 기준 계약금 10%를 언제까지 납부해야 하는지는, 내가 서명하는 매매계약서(특약 포함) 와 사업주체/조합이 제시한 공고·안내문 에 적힌 납부 일정이 기준이 됩니다. 실제 공고문에서는 분양대금 납부의 큰 틀(계약금→중도금→잔금)을 먼저 안내하고, 상세 일정은 별도 표나 유의사항으로 제시하는 방식이 흔합니다. 또, 계약서 문구에 따라 지급 시점이 조건부로 설정될 수도 있습니다. 예를 들어 한 사례 소개 자료에서는 용역계약서에 잔금(10%) 지급시기가 “사업승인 후”로 기재되어 있었다는 점이 언급됩니다. 이런 식으로 ‘사업 단계’와 지급을 연동하는 문구가 들어가면, 질문의 답은 계약서 문구를 확인해야만 확정됩니다. 관련 내용은 링크 에서 문구 사례를 확인할 수 있습니다. 2) 입주자모집공고에서 확인되는 ‘납부 순서’와 잔금 마감 시점 공고문에 적힌 문구를 보면, 납부 순서와 잔금 마감에 대한 기준이 비교적 명확하게 제시되는 경우가 있습니다. 예를 들어 한 입주자모집공고에는 “분양금액(주택가격)은 계약금, 중도금, 잔금의 순서로 납부”하며 “잔금은 입주(열쇠 수령일) 전에 완납”해야 한다고 안내되어 있습니다. (문구 확인: 링크 ) 이 문구가 의미하는 바는 최소 2가지입니다. 분양/공급 형태의 문서에서는 ‘계약금→중도금→잔금’ 흐름이 공식적으로 안내될 수 있습니다. 잔금은 “입주(열쇠 수령)” 이전에 완납해야 한다는 마감 기준이 문서에 적혀 있을 수 있습니다. 다만, 위 공고문 문구는 잔금 마감에 대한 기준을 보여주지만, 계약금 10%의...
윤석열 전 대통령 탄핵 인용 소식을 접하면, 가장 궁금한 지점은 ‘헌재가 정확히 무엇을 위헌·위법으로 봤는가’입니다. 또한 탄핵과 별개로 진행되는 형사재판(내란 우두머리 혐의 등)이 어디까지 왔는지도 함께 정리할 필요가 있습니다. 아래 내용은 제공된 기사/게시물 스니펫과 링크에서 확인되는 범위만 모아, 일반인이 흐름을 이해하기 쉽게 정리한 것입니다. 1) 탄핵 인용 관련: 스니펫에서 확인되는 ‘판단의 골격’ 제공된 근거 중 조국혁신당 사이트에는 헌법재판소가 윤석열 탄핵 심판에서 “피청구인의 위헌·위법행위는 국민 신임 …”이라는 취지로 판단했다는 문장이 인용돼 있습니다( 링크 ). 이 인용문만 놓고 보면, ‘위헌·위법행위’가 있었는지와 그로 인해 ‘국민의 신임’이 어떻게 평가됐는지가 핵심 축으로 소개됩니다. 다만 질문에서 요청하신 세부 항목, 즉 비상계엄 선포 자체를 문제 삼은 구체적 이유, 계엄 이후 조치(포고령, 국회 통제 등)의 어떤 지점이 헌법 위반인지, 국회의 권한행사 방해 및 정치활동 제약을 어떤 논리로 판단했는지 등은, 이번에 제공된 근거의 제목/스니펫만으로는 조항·사실관계·판단 구조가 그대로 제시돼 있지 않습니다. 따라서 이 글에서는 ‘헌재가 무엇을 문제 삼았다’는 세부 리스트를 단정적으로 재구성하기보다, 현재 확인 가능한 문구 수준의 요약(위헌·위법행위 → 국민 신임의 문제로 평가)까지만 적습니다. 만약 헌재 결정문 전문(주문 및 이유)이 추가로 확인되면, 그때는 문장 단위로 ‘어떤 행위’와 ‘어떤 헌법 원리/조항’이 연결되는지(예: 권력분립, 국회의 권한, 정치적 기본권 등) 구조화해 정리하는 것이 가장 정확합니다. 2) 형사 절차(내란 혐의) 관련: 체포영장과 1심 선고 언급 탄핵 심판과 별도로, 12·3 비상계엄 사태로 내란 혐의를 받는 윤석열 대통령에 대해 2024년 12월 31일 체포 영장이 발부됐다는 BBC 보도가 있습니다( 링크 ). 해당 보도는 ‘현직 대통령’에 대한 체포영장 발부라는 점을 함께 언급합니다. 또...





0 댓글