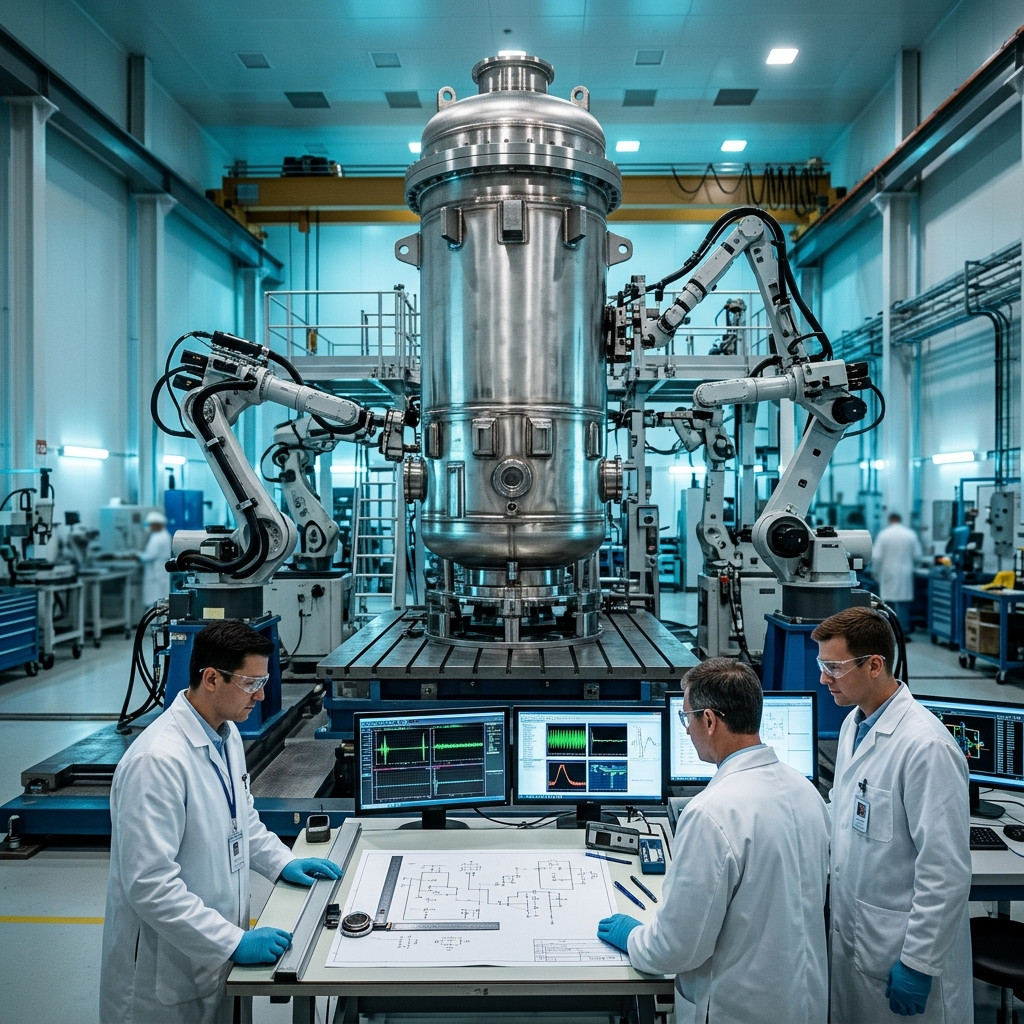
▲ 두산에너빌리티 창원 플랜트에서 전문 엔지니어들이 세계 5번째로 독자 개발한 H급 대형 가스터빈과 원자로 주기기 부품을 정밀 가공·조립하고 있다. / 보도자료사진
◈ 만인의 탑 핵심 에디토리얼 브리핑
3분기 어닝 서프라이즈: 연결 기준 매출 4조 4,495억원(+14.7%), 영업이익 2,612억원(+90.5%) 달성, 컨센서스 6.4% 상회
체코 악재의 팩트 분리: 단순 토목 '시공' 협상 결렬과 5조 6,401억원 규모 '핵심 주기기 공급계약'은 완전히 별개
SMR 파운드리 독점화: 뉴스케일파워·테라파워·엑스-에너지 등 미국 3대 SMR 설계사 핵심 기자재 전면 수주
AI 데이터센터 가스터빈 돌풍: 빅테크 자체 발전 수요 급증, 일론 머스크 xAI 테네시 데이터센터향 H급 가스터빈 공급
두산에너빌리티가 2026년 3분기 원자력과 가스터빈 등 고수익 사업의 비중 확대에 힘입어 영업이익이 전년 동기 대비 90% 이상 급증하는 견조한 실적을 거두었다. 한편 최근 한국수력원자력과 대우건설 컨소시엄의 체코 원전 시공 협상이 결렬되며 주가가 단기 급락세를 보였으나, 증권가에서는 5조 6,000억원 규모의 핵심 주기기 공급계약은 변함없이 유지되고 있어 기업가치 훼손은 제한적이라는 분석이 지배적이다. 오히려 소형모듈원자로(SMR)와 독자 개발 가스터빈 수주가 폭발적으로 증가하면서 중장기 성장 동력이 더욱 공고해지고 있다는 평가가 나온다.
1. 3분기 실적 팩트 체크: 고마진 사업 확대로 영업이익 90.5% 급증
두산에너빌리티가 공시한 2026년 3분기 잠정 실적에 따르면, 연결 기준 매출액은 4조 4,495억원, 영업이익은 2,612억원을 기록했다. 이는 전년 동기 대비 매출액이 14.7%, 영업이익이 90.5% 증가한 수치로, 영업이익률은 기존 3.5%에서 5.9%로 2.4%포인트 상승했다. 시장 컨센서스인 영업이익 2,450억원 안팎을 약 6.4% 상회하는 호실적이다.
3분기 누적 연결 실적을 살펴보면 매출액 13조 4,354억원, 영업이익 8,090억원으로 전년 동기 대비 각각 10.1%, 46.9% 증가했다. 당기순이익 역시 3,015억원으로 97.6% 급증하며 외형 성장과 질적 수익성 개선을 동시에 입증했다.
구분 (연결 기준)
2026년 3분기
2025년 3분기
전년 동기 대비 (YoY)
2026년 3분기 누적
전년 동기 대비 (YoY)
매출액
4조 4,495억원
3조 8,804억원
+14.7%
13조 4,354억원
+10.1%
영업이익
2,612억원
1,371억원
+90.5%
8,090억원
+46.9%
당기순이익
149억원
-
흑자전환
3,015억원
+97.6%
영업이익률 (OPM)
5.9%
3.5%
+2.4%p
6.0%
+1.5%p
이러한 어닝 서프라이즈의 핵심 동력은 두산에너빌리티 본업인 에너빌리티 부문의 수익성 대폭 개선이다. 에너빌리티 부문의 3분기 매출액은 1조 8,249억원, 영업이익은 1,211억원을 달성하며 영업이익률 6.6%를 기록했다. 영업이익은 전년 동기 434억원 수준 대비 179.0% 급증했다.
실적 개선의 주된 원인은 오만 미스파(Misfah) 및 두쿰(Duqm), 사우디아라비아 자푸라(Jafurah) 가스복합발전소 프로젝트와 체코 두코바니(Dukovany) 원전 프로젝트의 공정 진행에 따른 매출 인식 확대다. 특히 수익성이 높은 원자력 기자재와 H급 가스터빈 부문의 매출 비중이 커지면서 사업 포트폴리오의 고마진화가 본격화되었다.
2. 체코 두코바니 원전 악재의 진실: '시공' 결렬 vs '주기기 공급' 유지
시장에서 최근 주가 변동성을 키운 악재는 한국수력원자력과 대우건설·두산에너빌리티 컨소시엄 간의 체코 두코바니 신규 원전 시공계약 협상 결렬 발표였다. 공사비 산정과 위험 분담 조건에 대한 이견으로 한수원이 기존 컨소시엄과의 시공 협상을 종료하고 2027년 7월 신규 시공사 선정을 위한 재입찰을 추진하기로 하면서 시장에 악재로 작용했다.
그러나 증권가 전문가들은 시공 협상 결렬과 두산에너빌리티의 본업 경쟁력 간의 구분을 엄격히 해야 한다고 지적한다. 이번 결렬은 단순 토목·건설 분야의 시공(Construction)에 국한된 사안이며, 두산에너빌리티가 맡은 핵심 사업인 주기기 공급계약과는 완전히 별개다. 두산에너빌리티가 체결한 체코 두코바니 5·6호기 원자로 설비(NSSS) 및 터빈발전기(TG) 공급계약 5조 6,401억원은 한수원과의 발주 계약으로 이미 확정되어 정상 진행 중이다.
또한 두산에너빌리티는 시공 컨소시엄에서 주간사인 대우건설을 지원하는 비주간사 역할을 수행했으므로 시공 결렬에 따른 직접적 타격이 미미하다. 오히려 3년 전부터 체코 현지에 인력을 상주시키며 현장 자료를 확보하고 초기 인허가에 참여해 온 만큼, 2027년 신규 시공사 입찰 시 기자재 설치와 시공을 일괄 수행할 수 있는 독보적 위치를 점하고 있어 주가 과매도에 대한 반등 여력이 충분하다는 평가다.
▲ 차세대 소형모듈원자로(SMR) 전용 정밀 제작 클린룸에서 엔지니어들이 핵심 모듈의 초음파 비파괴 검사와 로봇 용접 품질을 정밀 진단하고 있다. / 보도자료사진
3. '차세대 먹거리' SMR과 가스터빈: 미국 빅테크 및 3대 개발사 싹쓸이
체코 원전 이슈의 노이즈에도 불구하고, 두산에너빌리티의 수주잔고와 신규 파이프라인은 사상 최대 수준을 향해 가고 있다. 3분기 말 기준 누적 수주잔고는 26조 5,805억원으로 전년 동기 대비 70.9% 증가했다. 3분기 누적 신규 수주는 9조 9,990억원으로 전년 동기 대비 85.5% 늘어나며 연간 목표인 13조 3,000억원의 75.2%를 달성했다.
글로벌 SMR 시장에서 두산에너빌리티는 설계사의 위탁을 받아 주기기를 전담 제작하는 'SMR 파운드리' 입지를 공고히 하고 있다. 뉴스케일파워(NuScale Power)의 상부 원자로 모듈 제작 계약, 빌 게이츠가 설립한 테라파워(TerraPower)의 나트륨(Natrium) SMR 주기기 3종 공급 계약, 엑스-에너지(X-energy)의 Xe-100 16기 분량 단조품 예약 계약을 체결하며 미국 3대 SMR 개발사 모두와 전략적 공급망을 완성했다. 창원 본사에 8,068억원을 투자해 구축 중인 SMR 전용 공장은 2031년까지 연간 20기 규모의 부품 공급 능력을 갖추게 된다.
AI 생태계 확장에 따른 글로벌 전력 부족 현상도 두산에너빌리티의 독자 개발 H급 가스터빈 수주를 폭발적으로 견인하고 있다. 빅테크 기업들이 전력망 연결 대기 시간을 줄이기 위해 자체 천연가스 발전을 도입하면서, 일론 머스크의 xAI 테네시 데이터센터향 H급 가스터빈 5기 수주를 비롯한 공급 실적이 급증하고 있다. 가스터빈은 30년 이상 고온 환경에서 가동되므로 1기당 연간 100억~120억원 규모의 고마진 장기 유지보수 서비스(LTSA) 수익이 지속 발생하는 알짜 사업이다.
4. 증권가 목표가 일제히 하향에도 '과도한 낙폭, 저가 매수 기회' 낙관론 팽배
체코 원전 시공 협상 결렬과 대형 원전 수주의 단기 모멘텀 시차를 반영하여 메리츠증권, 키움증권, 신한투자증권 등 주요 증권사들은 목표주가를 하향 조정했다. 그러나 투자의견은 일제히 '매수(BUY)'를 유지하며 주가 급락을 저가 매수 기회로 활용할 것을 권고했다. 목표주가 하향은 실적 악화가 아닌 시장 눈높이와 밸류에이션 멀티플 조정에서 비롯된 것이며, 현 주가 대비 40~80%의 높은 상승 여력이 존재한다는 분석이다.
증권사
기존 목표주가
변경 목표주가
투자의견
주요 분석 요지
메리츠증권
131,000원
109,000원
매수 (BUY)
과도한 주가 낙폭, 바닥권 저가 매수 진입 유효
신한투자증권
135,000원
110,000원
매수 (BUY)
체코 시공 결렬과 5.6조원 주기기 공급계약은 별개
키움증권
130,000원
100,000원
매수 (BUY)
단일 시공 리스크 대비 주가 하락 과도, 수주 파이프라인 견고
하나증권
120,000원
100,000원
매수 (BUY)
3분기 실적 개선 명확, 단기 불확실성 반영해 멀티플 조정
대신증권
100,000원
85,000원
매수 (BUY)
대형 원전 수주 본격화 2027년 하반기 전망, SMR 수주 긍정적
5. 향후 과제 및 투자 판단 포인트: 4분기 수주 3.3조 달성과 재무 부담 관리
두산에너빌리티는 4분기 중 SMR 분야 약 1조원, 복합화력 주기기 약 1조원, 해상풍력 7,000억원 등 약 3조 3,000억원 이상의 추가 수주를 달성해 연간 목표 13조 3,000억원을 완수한다는 구상이다. 3분기 말 순차입금이 4조 4,548억원으로 늘어나며 부채비율이 145.6%로 상승했으나, 이는 SMR 및 가스터빈 설비 증설을 위한 선제적 CAPEX 투자에 기인한다. 2027년부터 선수금 유입과 고수익 매출이 본격 반영되면서 현금흐름이 획기적으로 개선될 전망이다.
6. 종합 평가 및 전망: 체질 개선 가속화와 장기 성장 궤도
결론적으로 두산에너빌리티는 시공 협상 마찰이라는 일시적 노이즈를 겪었으나 5.6조원 규모 핵심 주기기 공급권이라는 실속을 완벽히 지켜냈다. 3분기 실적에서 입증된 가스터빈과 원전 부문의 고마진 체질, 미국 3대 SMR 개발사 및 AI 데이터센터 가스터빈 수주 모멘텀은 기업의 본질가치를 더욱 견고하게 뒷받침하고 있다.
언론사 등록번호: 서울 아-54218 / 매체명: 만인의 탑 (Young's Daily News)
▲ Precision engineers assemble an advanced H-class large gas turbine and key nuclear reactor components inside Doosan Enerbility's Changwon manufacturing facility. / Press Photo
◈ Manintop Key Editorial Executive Briefing
Q3 Earnings Surge: Consolidated revenue of 4.4495 trillion KRW (+14.7%) and operating profit of 261.2 billion KRW (+90.5%), beating consensus by 6.4%
Czech Noise Decoupling: Civil construction negotiation termination strictly isolated from the binding 5.6401 trillion KRW main equipment supply contract
SMR Foundry Dominance: Major equipment fabrication contracts secured across all top three US SMR designers (NuScale Power, TerraPower, X-energy)
AI Data Center Gas Turbines: Soaring on-site power generation demand from global hyperscalers, including five H-class units for Elon Musk's xAI data center
Doosan Enerbility achieved robust financial performance in the third quarter of 2026, with operating profit surging over 90 percent year-on-year, propelled by the expanding proportion of high-margin nuclear power and gas turbine operations. Although share prices experienced a sharp short-term retreat following the breakdown of construction negotiations between Korea Hydro and Nuclear Power (KHNP) and the Daewoo E&C consortium for the Czech nuclear project, securities analysts widely assess that the fundamental corporate valuation remains intact, given that the 5.6 trillion KRW main equipment supply contract remains fully operational. Furthermore, explosive order growth in Small Modular Reactors (SMRs) and proprietary gas turbines is cementing the company's mid- to long-term growth engine.
According to Doosan Enerbility's provisional third-quarter 2026 disclosure, consolidated revenue reached 4.4495 trillion KRW and operating profit registered 261.2 billion KRW. This represents a 14.7 percent increase in revenue and a 90.5 percent surge in operating profit compared to the prior-year period, with the operating profit margin expanding by 2.4 percentage points from 3.5 percent to 5.9 percent. These results comfortably exceeded the market consensus estimate of approximately 245.0 billion KRW by roughly 6.4 percent.
On a cumulative basis through the third quarter, consolidated revenue reached 13.4354 trillion KRW and operating profit recorded 809.0 billion KRW, representing gains of 10.1 percent and 46.9 percent year-on-year, respectively. Net profit also leaped by 97.6 percent to 301.5 billion KRW, demonstrating concurrent top-line expansion and qualitative profitability enhancement.
Category (Consolidated)
Q3 2026
Q3 2025
YoY Change
Cumulative Q3 2026
YoY Change
Revenue
4.4495 Trillion KRW
3.8804 Trillion KRW
+14.7%
13.4354 Trillion KRW
+10.1%
Operating Profit
261.2 Billion KRW
137.1 Billion KRW
+90.5%
809.0 Billion KRW
+46.9%
Net Profit
14.9 Billion KRW
-
Turnaround
301.5 Billion KRW
+97.6%
Operating Margin (OPM)
5.9%
3.5%
+2.4%p
6.0%
+1.5%p
The primary driver behind this earnings surprise was the remarkable profitability improvement in the core Enerbility business division. The Enerbility segment generated revenue of 1.8249 trillion KRW and operating profit of 121.1 billion KRW in the third quarter, achieving an operating margin of 6.6 percent. Operating profit surged by 179.0 percent compared to the 43.4 billion KRW posted during the corresponding quarter of the previous year.
The earnings expansion was primarily catalyzed by progressive revenue recognition from the Misfah and Duqm combined-cycle power projects in Oman, the Jafurah gas project in Saudi Arabia, and ongoing engineering progress on the Czech Dukovany nuclear project. In particular, the enlarged revenue contribution from high-margin nuclear equipment and advanced H-class gas turbines has accelerated the structural shift of the corporate portfolio toward superior margins.
2. Unpacking the Czech Nuclear Noise: Civil Construction Impasse vs Binding Main Equipment Supply
The principal headwind that triggered recent share price volatility was the announcement of terminated construction negotiations between KHNP and the Daewoo E&C-Doosan Enerbility consortium for the new Dukovany nuclear units. Due to divergences over construction cost indexing and risk-sharing terms, KHNP concluded discussions with the incumbent consortium and decided to initiate a re-tender to select a new construction contractor by July 2027, creating temporary market headwinds.
Nevertheless, equity research analysts emphasize the critical distinction between the construction contract deadlock and Doosan Enerbility's core industrial competitiveness. This impasse pertains strictly to civil engineering and structural construction, remaining entirely insulated from the main equipment supply mandate. The 5.6401 trillion KRW supply contract secured by Doosan Enerbility for the nuclear steam supply system (NSSS) and turbine generators (TG) for Dukovany Units 5 and 6 is already legally finalized with KHNP and proceeds without disruption.
Moreover, Doosan Enerbility functioned as a non-lead consortium partner supporting prime contractor Daewoo E&C in civil construction, meaning the direct financial exposure from the construction breakdown is negligible. Having maintained on-site personnel in the Czech Republic for over three years to accumulate field survey data and participate in preliminary licensing, Doosan Enerbility occupies an unparalleled position to execute integrated equipment installation and construction during the 2027 re-bidding, providing substantial upside potential from oversold valuations.
▲ Inside a specialized cleanroom manufacturing facility for Small Modular Reactors (SMRs), nuclear engineers conduct ultrasound non-destructive testing and automated precision robotic weld diagnostics on primary pressure modules. / Press Photo
3. Next-Generation Growth Engines: Sweeping Global SMR Designers and AI Hyperscaler Turbines
Notwithstanding the noise surrounding the Czech project, Doosan Enerbility's order backlog and forward pipeline continue toward historic zeniths. As of the end of the third quarter, the cumulative order backlog stood at 26.5805 trillion KRW, up 70.9 percent from the previous year. Cumulative new orders through the third quarter reached 9.9990 trillion KRW, an 85.5 percent year-on-year increase that fulfills 75.2 percent of the annual target of 13.3 trillion KRW.
In the global SMR landscape, Doosan Enerbility is firmly consolidating its position as the premier 'SMR Foundry,' fabricating nuclear island components under technical commission. By securing upper reactor module manufacturing agreements with NuScale Power, tripartite core equipment supply contracts for TerraPower's Natrium SMR founded by Bill Gates, and forging reservation pacts for 16 Xe-100 reactor units with X-energy, the company has completed strategic alliances across all three major American SMR pioneers. A dedicated 806.8 billion KRW SMR manufacturing plant under construction in Changwon will establish an annual supply capacity of 20 reactor module sets by 2031.
Simultaneously, the acute global power shortages generated by expanding artificial intelligence infrastructure are driving exponential demand for Doosan Enerbility's proprietary H-class gas turbines. Major cloud and tech enterprises are adopting on-site natural gas generation to bypass multi-year electrical grid interconnection delays, yielding major supply wins such as five H-class gas turbines for Elon Musk's xAI Tennessee data center. Because gas turbines operate in severe thermal environments for more than thirty years, each installed unit generates highly lucrative long-term service agreements (LTSA) yielding 10 to 12 billion KRW annually.
4. Institutional Consensus: Target Price Revisions vs Unanimous 'BUY' Recommendations on Excessive Sell-Off
Reflecting the construction negotiation impasse and the temporary timing delay in mega-nuclear project orders, major securities houses, including Meritz, Kiwoom, and Shinhan Securities, revised their target prices downward. Nonetheless, all major brokerage houses maintained unanimous 'BUY' ratings, advising market participants to utilize the sharp sell-off as an attractive entry window. Analysts emphasize that target price adjustments reflect valuation multiple recalibrations and elevated market expectations rather than fundamental operational deterioration, indicating upside potential ranging from 40 to 80 percent from current trading levels.
Securities House
Previous Target
Revised Target
Recommendation
Key Analytic Rationale
Meritz Securities
131,000 KRW
109,000 KRW
BUY
Excessive sell-off presents a compelling bottom-fishing entry opportunity
Shinhan Securities
135,000 KRW
110,000 KRW
BUY
Czech civil construction impasse fully detached from the 5.6T KRW main equipment supply contract
Q3 profitability expansion verified; multiple trimmed purely to account for short-term sentiment
Daishin Securities
100,000 KRW
85,000 KRW
BUY
Mega-nuclear order inflection anticipated in 2H 2027; early SMR bookings establish strong baseline
5. Strategic Outlook & Risk Parameters: Q4 3.3 Trillion KRW Target and Capital Discipline
During the fourth quarter, Doosan Enerbility aims to capture more than 3.3 trillion KRW in additional orders, encompassing approximately 1.0 trillion KRW in SMR contracts, 1.0 trillion KRW in combined-cycle power equipment, and 700 billion KRW in offshore wind, thereby completing its 13.3 trillion KRW annual booking target. While net debt rose to 4.4548 trillion KRW at the end of the third quarter, lifting the debt-to-equity ratio to 145.6 percent, this reflects pre-emptive capital expenditures dedicated to SMR plant construction and gas turbine capacity expansion. From 2027 onward, advance customer milestone payments and high-margin revenue recognition will substantially enhance corporate cash flows and stabilize leverage ratios.
6. Strategic Synthesis and Outlook: Accelerated Restructuring and Long-Term Trajectory
In conclusion, Doosan Enerbility navigated temporary friction in civil construction negotiations while flawlessly safeguarding its substantive 5.6 trillion KRW main equipment supply mandate. The robust high-margin operational structure validated in the third-quarter results, alongside sweeping commercial momentum with the top three US SMR designers and AI data center turbine deployments, decisively underpins the company's enduring intrinsic enterprise value.
Reported by: Manintop Business & Industry Analysis Desk
Editor-in-Chief: Dr. Seung Youb Ssin / young@youngsdaily.com
Press Registration: Seoul A-54218 / Publication: Young's Daily News (Manintop)
MANINTOP NEWSLETTER
📬 만인의 탑 뉴스레터 무료 구독
오늘 보신 정책·시사 뉴스가 유익하셨나요? 매일 엄선되는 알짜 복지 혜택과 국회 실시간 속보를 이메일로 가장 먼저 받아보세요. (평생 무료)
Computer Programmer who love programming.
Computer Programmer Who love Riding Bicycle.
Computer Programmer who love trip in abroad.
Computer Programmer who love studying about programming
- even if sometimes it's very boring.
Computer Programmer who love talking with person.
- I love communication with person.
1월이 시작되면 감기는 이미 우리 곁에 와 있습니다. 2월, 3월, 4월까지 이어지는 추위와 건조함은 코와 목을 가장 먼저 공격합니다. 아침에 일어나자마자 막혀 있는 코. 계속 흐르는 콧물. 괜히 칼칼해지는 목. 이 증상은 “시작”일 뿐입니다. 한 번 무너지면 일주일, 길면 한 달까지 끌고 갑니다. 약을 먹으면 잠깐 괜찮아집니다. 하지만 며칠 뒤 또 반복됩니다. 왜일까요? 감기는 ‘치료’의 문제가 아니라 ‘관리’의 문제이기 때문입니다. 대부분은 감기가 오고 나서 약을 찾습니다. 하지만 진짜 중요한 건 감기가 오기 전에 코와 목을 지키는 것입니다. 건조한 실내 공기, 차가운 바깥 공기, 눈에 보이지 않는 세균. 코와 목은 매일 공격받고 있습니다. 지긋지긋하죠! 그런데도 우리는 아무 준비 없이 버티고 있습니다. 이번 겨울도 그렇게 보낼 건가요? 사실 방법은 어렵지 않습니다. 코를 깨끗하게 관리하고, 목을 따뜻하게 보호하고, 점막을 촉촉하게 유지하고, 기관지를 미리 관리하고, 외부 공기를 차단하는 것. 이 다섯 가지만 꾸준히 해도 감기약 없이 겨울을 보내는 것이 충분히 가능합니다. 🔥 이제부터 그 방법을 하나씩 살펴보겠습니다. 🔥 1. 코와 목을 먼저 관리해야 하는 과학적 이유 감기의 대부분은 코 점막에서 시작됩니다. 국제 학술지 Nature Reviews Microbiology 와 Journal of Allergy and Clinical Immunology 에 실린 호흡기 감염 관련 연구들에서는, 감기 바이러스가 비강 상피세포에 먼저 부착해 증식한다는 점을 설명하고 ...
리모델링사업이 진행 중인 아파트를 매매할 때 “계약금 10%를 언제까지 내야 하느냐”는 질문이 특히 많이 나옵니다. 이주공고(이주 안내)가 7~11월쯤이라고 들으면, 그 시점에 맞춰 계약금도 움직일 것 같아서 더 헷갈리기 쉽습니다. 하지만 실제 납부기한은 ‘이주공고가 언제냐’만으로 자동 결정되지 않는 경우가 많습니다. 1) 계약금 10% 납부기한: 결국 ‘문서에 적힌 일정’이 기준 계약금 10%를 언제까지 납부해야 하는지는, 내가 서명하는 매매계약서(특약 포함) 와 사업주체/조합이 제시한 공고·안내문 에 적힌 납부 일정이 기준이 됩니다. 실제 공고문에서는 분양대금 납부의 큰 틀(계약금→중도금→잔금)을 먼저 안내하고, 상세 일정은 별도 표나 유의사항으로 제시하는 방식이 흔합니다. 또, 계약서 문구에 따라 지급 시점이 조건부로 설정될 수도 있습니다. 예를 들어 한 사례 소개 자료에서는 용역계약서에 잔금(10%) 지급시기가 “사업승인 후”로 기재되어 있었다는 점이 언급됩니다. 이런 식으로 ‘사업 단계’와 지급을 연동하는 문구가 들어가면, 질문의 답은 계약서 문구를 확인해야만 확정됩니다. 관련 내용은 링크 에서 문구 사례를 확인할 수 있습니다. 2) 입주자모집공고에서 확인되는 ‘납부 순서’와 잔금 마감 시점 공고문에 적힌 문구를 보면, 납부 순서와 잔금 마감에 대한 기준이 비교적 명확하게 제시되는 경우가 있습니다. 예를 들어 한 입주자모집공고에는 “분양금액(주택가격)은 계약금, 중도금, 잔금의 순서로 납부”하며 “잔금은 입주(열쇠 수령일) 전에 완납”해야 한다고 안내되어 있습니다. (문구 확인: 링크 ) 이 문구가 의미하는 바는 최소 2가지입니다. 분양/공급 형태의 문서에서는 ‘계약금→중도금→잔금’ 흐름이 공식적으로 안내될 수 있습니다. 잔금은 “입주(열쇠 수령)” 이전에 완납해야 한다는 마감 기준이 문서에 적혀 있을 수 있습니다. 다만, 위 공고문 문구는 잔금 마감에 대한 기준을 보여주지만, 계약금 10%의...
윤석열 전 대통령 탄핵 인용 소식을 접하면, 가장 궁금한 지점은 ‘헌재가 정확히 무엇을 위헌·위법으로 봤는가’입니다. 또한 탄핵과 별개로 진행되는 형사재판(내란 우두머리 혐의 등)이 어디까지 왔는지도 함께 정리할 필요가 있습니다. 아래 내용은 제공된 기사/게시물 스니펫과 링크에서 확인되는 범위만 모아, 일반인이 흐름을 이해하기 쉽게 정리한 것입니다. 1) 탄핵 인용 관련: 스니펫에서 확인되는 ‘판단의 골격’ 제공된 근거 중 조국혁신당 사이트에는 헌법재판소가 윤석열 탄핵 심판에서 “피청구인의 위헌·위법행위는 국민 신임 …”이라는 취지로 판단했다는 문장이 인용돼 있습니다( 링크 ). 이 인용문만 놓고 보면, ‘위헌·위법행위’가 있었는지와 그로 인해 ‘국민의 신임’이 어떻게 평가됐는지가 핵심 축으로 소개됩니다. 다만 질문에서 요청하신 세부 항목, 즉 비상계엄 선포 자체를 문제 삼은 구체적 이유, 계엄 이후 조치(포고령, 국회 통제 등)의 어떤 지점이 헌법 위반인지, 국회의 권한행사 방해 및 정치활동 제약을 어떤 논리로 판단했는지 등은, 이번에 제공된 근거의 제목/스니펫만으로는 조항·사실관계·판단 구조가 그대로 제시돼 있지 않습니다. 따라서 이 글에서는 ‘헌재가 무엇을 문제 삼았다’는 세부 리스트를 단정적으로 재구성하기보다, 현재 확인 가능한 문구 수준의 요약(위헌·위법행위 → 국민 신임의 문제로 평가)까지만 적습니다. 만약 헌재 결정문 전문(주문 및 이유)이 추가로 확인되면, 그때는 문장 단위로 ‘어떤 행위’와 ‘어떤 헌법 원리/조항’이 연결되는지(예: 권력분립, 국회의 권한, 정치적 기본권 등) 구조화해 정리하는 것이 가장 정확합니다. 2) 형사 절차(내란 혐의) 관련: 체포영장과 1심 선고 언급 탄핵 심판과 별도로, 12·3 비상계엄 사태로 내란 혐의를 받는 윤석열 대통령에 대해 2024년 12월 31일 체포 영장이 발부됐다는 BBC 보도가 있습니다( 링크 ). 해당 보도는 ‘현직 대통령’에 대한 체포영장 발부라는 점을 함께 언급합니다. 또...




0 댓글